Education expenses vary in size and timing, and small changes can ripple through a household budget. A practical, repeatable approach keeps those costs predictable without sacrificing other goals. This article outlines ways to match funding to timing, create simple buckets, and handle trade-offs. These steps help families plan with clarity and adjust when priorities shift.
Assess Costs and Timing
Begin by listing upcoming education costs and noting exactly when each payment is due. Include tuition, recurring subscriptions, materials, travel, and any associated ancillary fees to capture the true cost. Estimate realistic amounts, including likely increases and price variability, so your figures are conservative rather than optimistic. Categorize items by urgency and flexibility so you can prioritize what must be covered immediately versus what can be delayed or reduced. The result is a timeline that clarifies cash flow pressure points and planning windows.
Documenting timing reduces surprises and makes budgeting simpler. Update figures at least quarterly or when a major change occurs. That discipline means fewer rushed decisions and steadier outcomes.
Build Flexible Funding Buckets
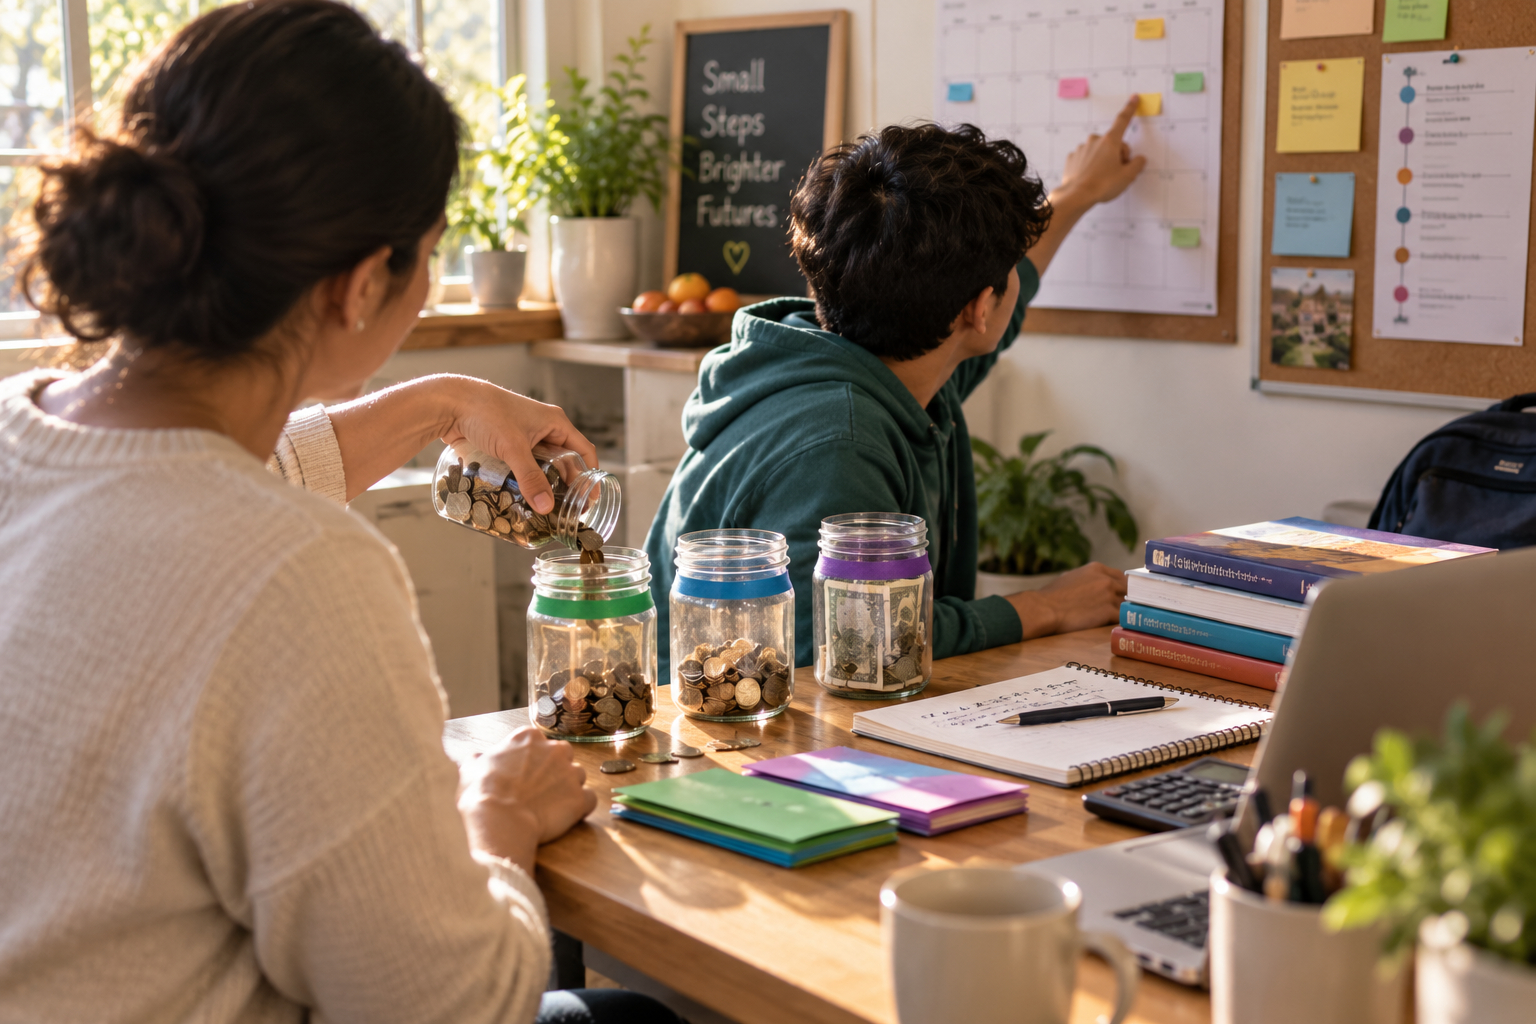
Instead of a single educational line item, create modular buckets for short-term fees, medium-term programs, and long-term investments tied to future goals. Decide a recurring contribution amount for each bucket based on the predicted timing and your household cash flow pattern. Use automatic transfers or standing allocations to seed buckets consistently and take emotion out of monthly decisions. Leave a small discretionary bucket for trial courses or one-off opportunities that can yield high value. Review bucket rules annually and adjust contribution rates as income or priorities change.
- Short-term: workshops, supplies, and subscriptions due within months.
- Medium-term: multi-month programs, certifications, or school terms.
- Long-term: degree programs, large tuition payments, or major training investments.
Treat buckets as guidelines rather than immutable rules so you can adapt to life events. A formal review cadence keeps the system responsive. Transparency across the household reduces conflicts about education spending.
Manage Trade-offs and Adjustments
When budgets tighten, apply a simple decision rule: protect essential learning linked to required credentials or clear career advancement while pausing lower-impact electives. Look for lower-cost substitutes such as open educational resources, group enrollments, or library access to preserve momentum at reduced cost. Factor in non-monetary trade-offs like time and attention to make choices that fit overall household capacity. Maintain a short checklist to evaluate new opportunities against current commitments: cost, timing, expected benefit, and alternatives. This structure helps you say no without second-guessing and keeps choices aligned with longer-term goals.
Communicate trade-offs across household members so choices reflect shared priorities. A short cooling-off period before large commitments reduces impulse purchases. Keep a contingency buffer to seize unexpected, high-value opportunities.
Conclusion
Calibrating your budget for education costs turns uncertainty into manageable steps. Use clear timing, modular buckets, and simple decision rules to stay adaptable. Small, consistent actions build reliable funding without overwhelming the household.