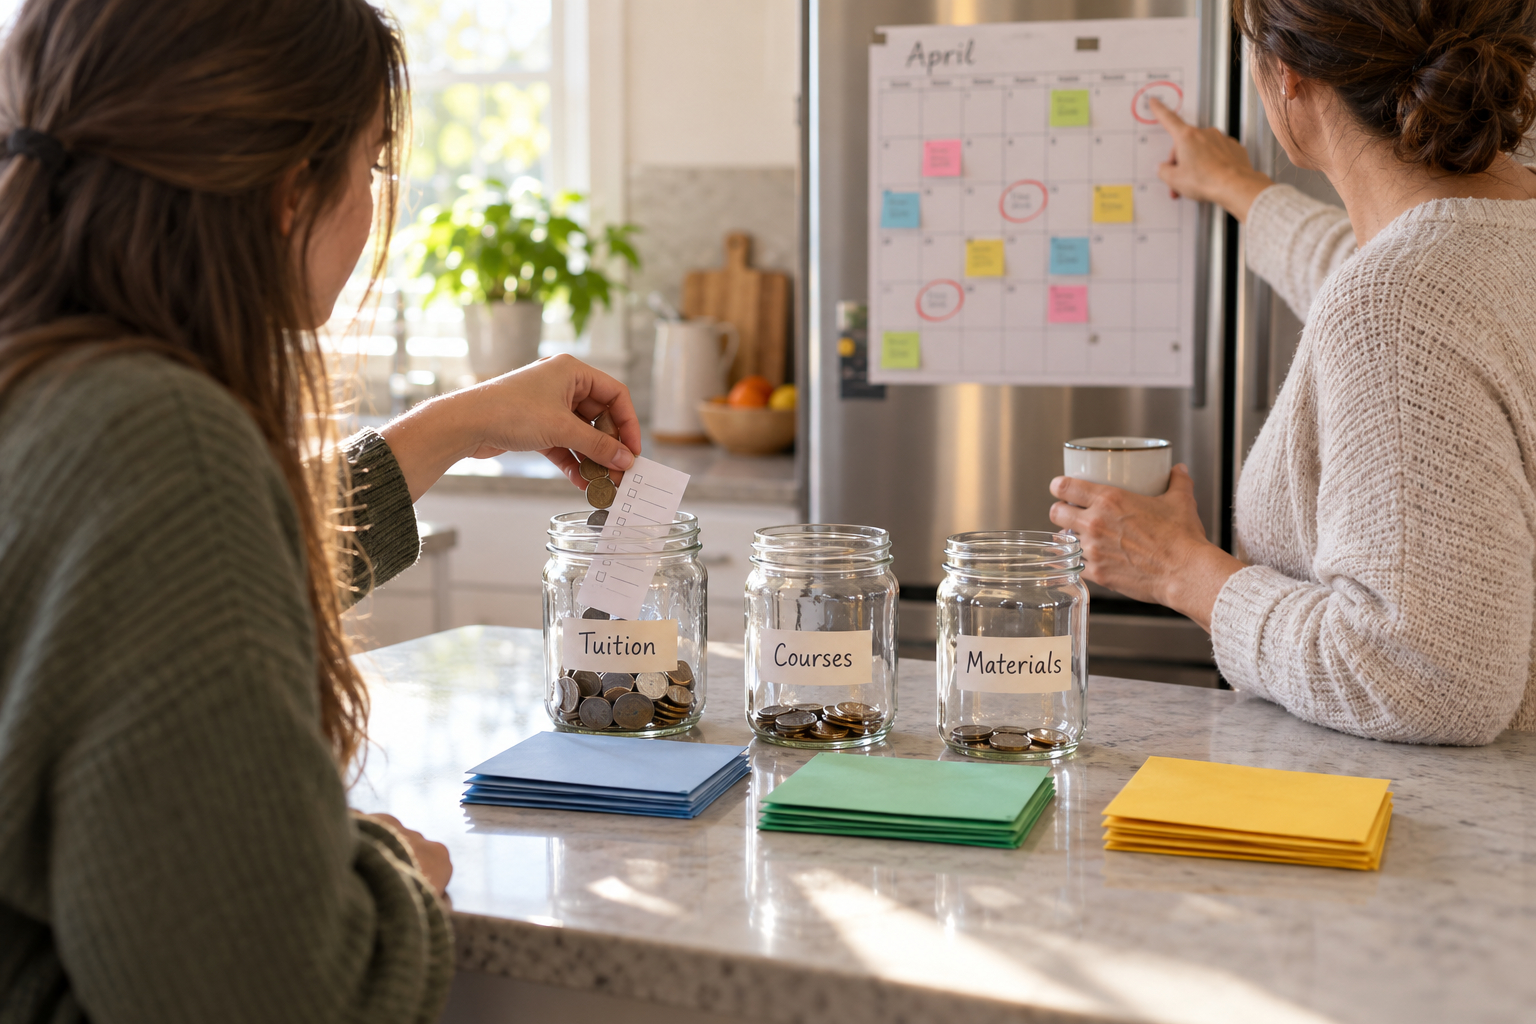
Planning how a household funds education expenses benefits from clear structure and simple rules that reflect family priorities and capacity. Breaking future and ongoing costs into understandable pieces reduces uncertainty and helps decisions stay aligned with priorities. A practical funding system focuses on timing, flexible buffers, and repeatable funding rules rather than perfect predictions, and includes simple governance for decisions. This article outlines steps to assess needs, build modular buckets, and operate a review rhythm to keep education spending sustainable and reduces stress around those choices.
Assessing Education Needs and Timing
Start by mapping known commitments and likely future costs across short, medium, and long horizons. Estimate timing and amounts for tuition, materials, supplemental courses, and incidental expenses to create realistic funding targets. Identify which costs are discretionary and which are core to progression to prioritize funding when resources are constrained. Factor in household cash flow cycles so contributions align with income timing.
Accurate categorization makes later choices easier. It also prevents overfunding low-priority items. Small, documented rules aid fairness and clarity in shared households.
Building Modular Funding Buckets
Create separate, clearly named buckets for immediate needs, planned milestones, and opportunity learning. Keep the immediate bucket liquid for upcoming payments, the milestone bucket invested conservatively for medium-term goals, and the opportunity bucket modestly funded for ad hoc courses. Each bucket should have simple target rules and thresholds that trigger funding or pausing decisions. This modular approach reduces stress and makes trade-offs visible.
- Immediate: upcoming fees and supplies.
- Milestone: planned certificate or degree costs.
- Opportunity: short courses and skill upgrades.
Labeling and segregating funds simplifies monthly budgeting. It also creates clear criteria for when to tap each bucket. That visibility makes it easier to prioritize limited funds when multiple needs coincide.
Operational Rules and Review Rhythm
Set straightforward rules such as percentage of monthly income, fixed contributions, or reallocations when priorities shift. Decide what constitutes a pause or a priority change and document who makes the decision in the household, and outline a fallback process for disputes. Run a quarterly check to compare targets with balances and upcoming needs, and adjust contributions rather than ad hoc spending when possible. Keeping rules simple boosts adherence and reduces decision fatigue.
Regular reviews catch small gaps before they become shortages. They also keep the system responsive as priorities evolve.
Conclusion
A durable household education funding system combines clear priorities, modular buckets, and simple operating rules. Regular review and modest buffers make the plan practical across varying income cycles. With this approach, education costs become manageable tasks rather than recurring crises.
Related Articles
Recent Posts

A Methodical Guide to Planning Education Expense Flows
Calendar-First Approach to Managing Recurring Education Expenses
Developing Transferable Note-Taking Frameworks for Learners
Helping Students Design Personal Learning Dashboards for Growth
Helping Students Craft Sustainable Independent Study Systems


