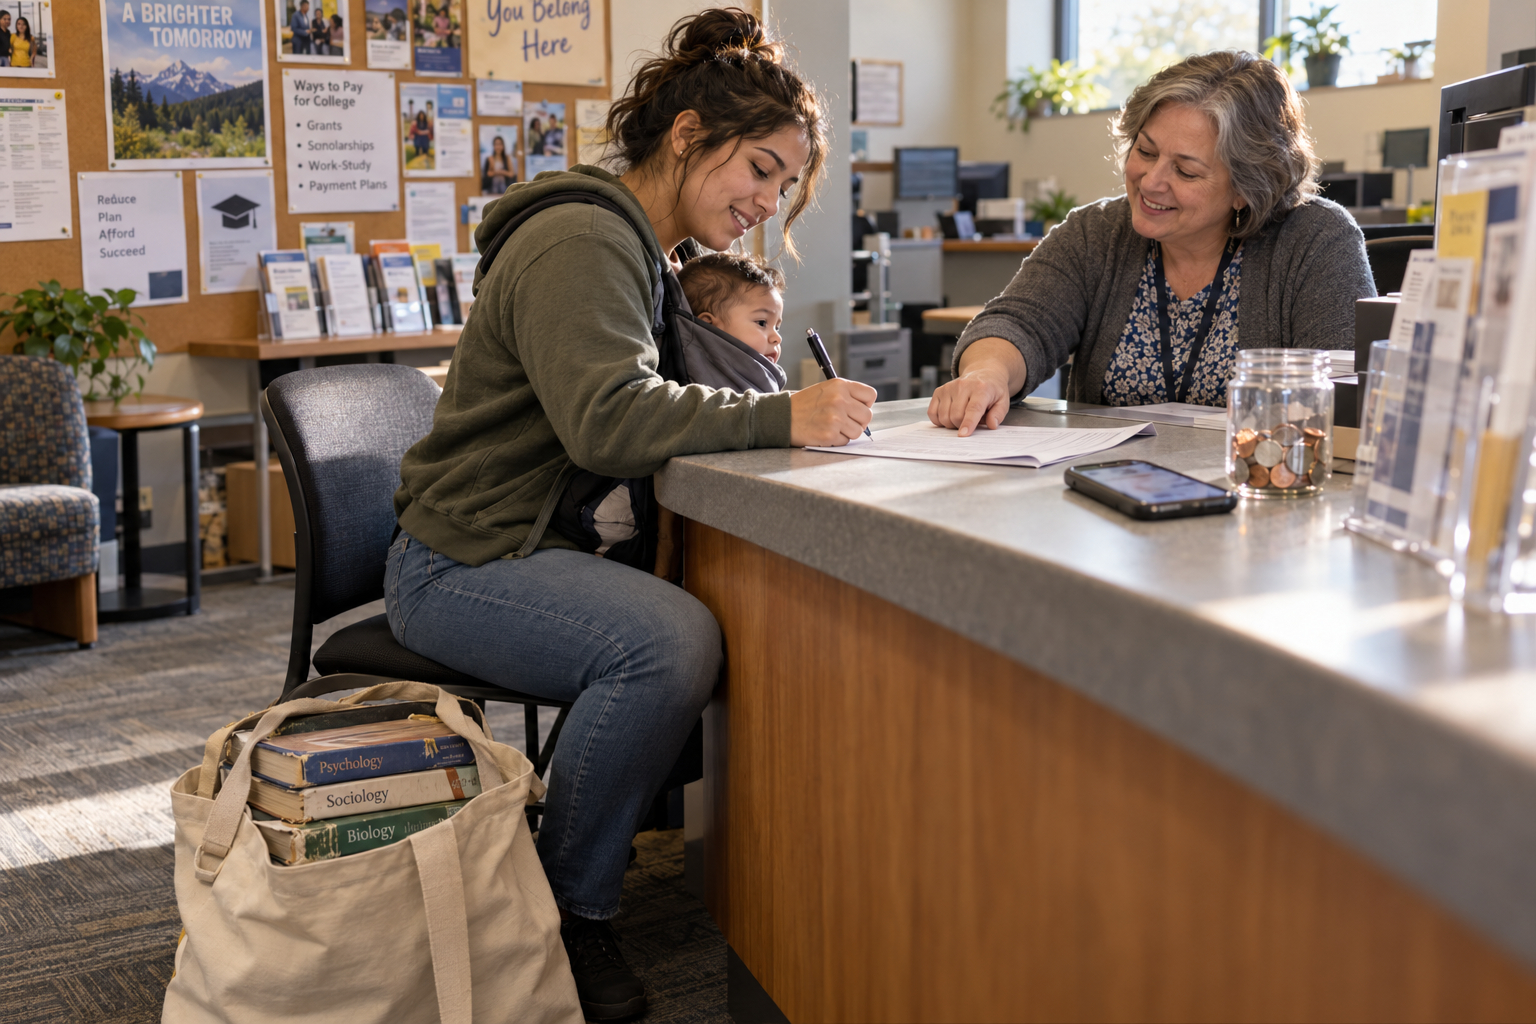
Education expenses sit in many household ledgers and can feel relentless when bills arrive. Small decisions about courses, materials, and timing often change the total more than sweeping cuts. By separating must-haves from nice-to-haves and planning payment timing, you keep control without sacrificing learning. The following sections offer clear, actionable approaches that work for short- and medium-term needs.
Prioritize What Delivers Value
Start by listing all education-related costs and rank them by direct impact on outcomes. Tuition and mandatory fees generally give the greatest return because they enable enrollment and credit; optional workshops or premium services belong lower unless they address a specific gap. Consider course content, credential recognition, and whether cheaper alternatives—open resources or community courses—cover the same basics. This ranking helps you decide where to direct limited funds first.
Keep priorities visible when new expenses appear. A short checklist prevents impulse spending and ensures money goes to what matters most.
Tactics to Reduce Outlays Without Losing Quality
There are straightforward ways to lower costs without shrinking learning. Buy used textbooks, share materials, or choose digital editions where appropriate to cut supply expenses. Time purchases to sales cycles and assess whether bundled services are actually cheaper than picking items à la carte. Shop for accredited, lower-cost course providers that meet your needs rather than defaulting to the most familiar names.
Also negotiate when possible: payment plans, installment arrangements, or waivers can make large bills manageable. Small savings repeated over semesters add up to meaningful relief.
Funding Options and Smoothing Payments
Evaluate short-term and medium-term funding choices by total cost and flexibility. Interest-free payment plans or employer-sponsored tuition assistance often beat loans with high interest, while savings set aside specifically for education prevent expensive borrowing. If borrowing is necessary, prefer lower-rate options and clear repayment terms to avoid surprises. Track cash flow to align major payments with income peaks or tax advantages like education credits when available.
Automate contributions to a designated education fund and review it each term. Predictability reduces stress and makes it easier to spot when adjustments are needed.
Conclusion
Cut costs by prioritizing essentials and using practical savings tactics. Smooth payments with targeted funding choices and automated savings. With clear priorities, modest changes yield steady, sustainable progress.
Related Articles
Recent Posts

Where to Spend and Where to Save on Education
NASA telescope is on the verge of plunging back to Earth after failed rescue mission
Midterm results could bring brewing student loan battle to a head
Manage Education Costs with Realistic, Everyday Choices
Education Department posts doctored image showing its HQ as Spirit Halloween


