Education expenses add up in many small places: course fees, materials, software, travel and time. Deciding which costs truly boost skills or credentials is the difference between an investment and an avoidable expense. This article offers a practical way to match spending to the learning outcomes you care about. Read on to find straightforward steps you can start using this month.
Assess the real value of each expense
Start by listing every recurring and one‑time education cost, then attach a clear learning outcome to each item. Ask whether a course, certification, or tool directly improves a skill employers or your personal goals will notice. Consider alternatives that deliver the same outcome for less money, such as peer study groups, open educational resources, or targeted micro‑courses. This evaluation turns vague costs into decisions you can justify to yourself and others.
Be honest about sunk costs and emotional purchases that don’t move the needle. Removing low‑value items frees budget for things that matter more.
Cut costs without sacrificing learning quality
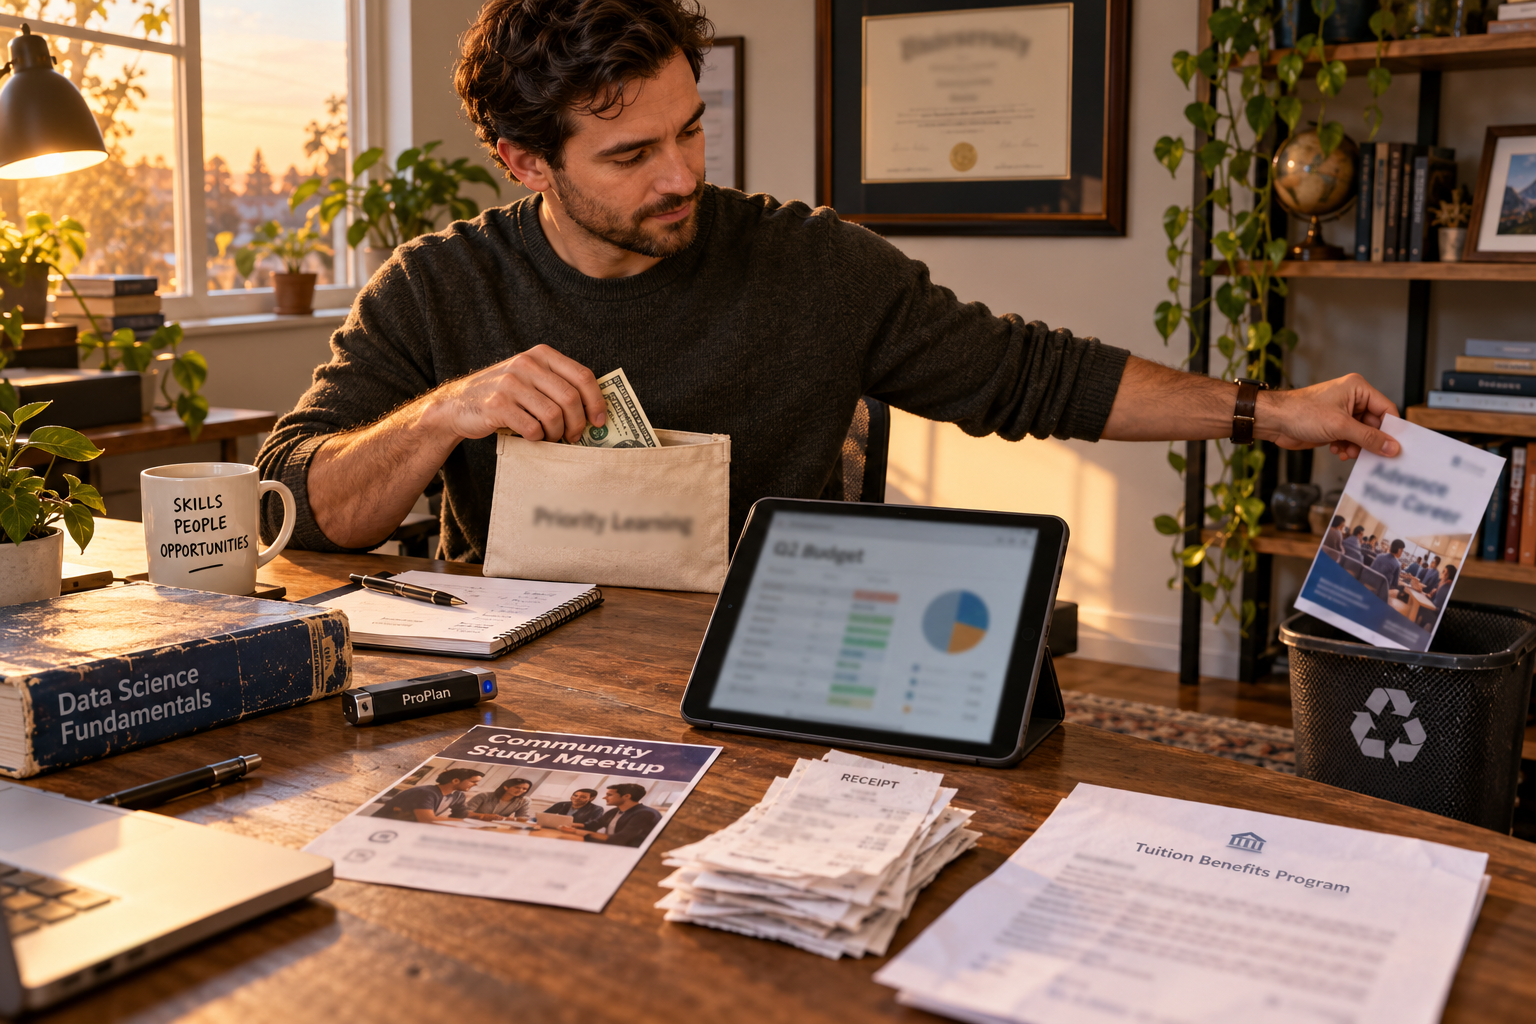
Saving money doesn’t have to mean lower quality. Choose low‑cost entry points where you can test interest before committing to advanced programs. Share resources: split textbook purchases, swap skill sessions with peers, or use library and employer subscriptions. When tuition or fees are necessary, negotiate discounts, ask about payment plans, or look for scholarships and employer tuition benefits.
- Buy used or digital materials when possible.
- Prioritize hands‑on projects over expensive theory that has little practical return.
Small predictable cuts compound over time, making room for higher‑impact investments later.
Time your investments and diversify funding
When you pay matters as much as what you pay for. Plan major expenses around periods when you can maximize benefit — for example, just before a job review or when a capstone project will be most relevant. Mix funding sources: savings, employer support, targeted loans, and income set aside specifically for education. Avoid high‑interest borrowing for short courses unless the expected return is clear and quick.
Keeping a simple timeline with cost, funding source, and expected payoff helps you make smarter, less emotional choices.
Build flexibility and review regularly
Set a modest, recurring education budget and treat it like any other household account that you review quarterly. Track outcomes: did a course lead to a promotion, new clients, or measurable skill growth? If not, reallocate funds to other formats or topics. Maintain a small reserve for unexpected opportunities such as workshops or time‑limited scholarships.
Regular review keeps spending aligned with real results and prevents habitual purchases that no longer serve your goals.
Conclusion
Aligning spending with clear learning goals reduces waste and increases impact. Regularly evaluate costs, time purchases for maximum payoff, and keep a flexible budget. Those habits make education spending both sustainable and effective.