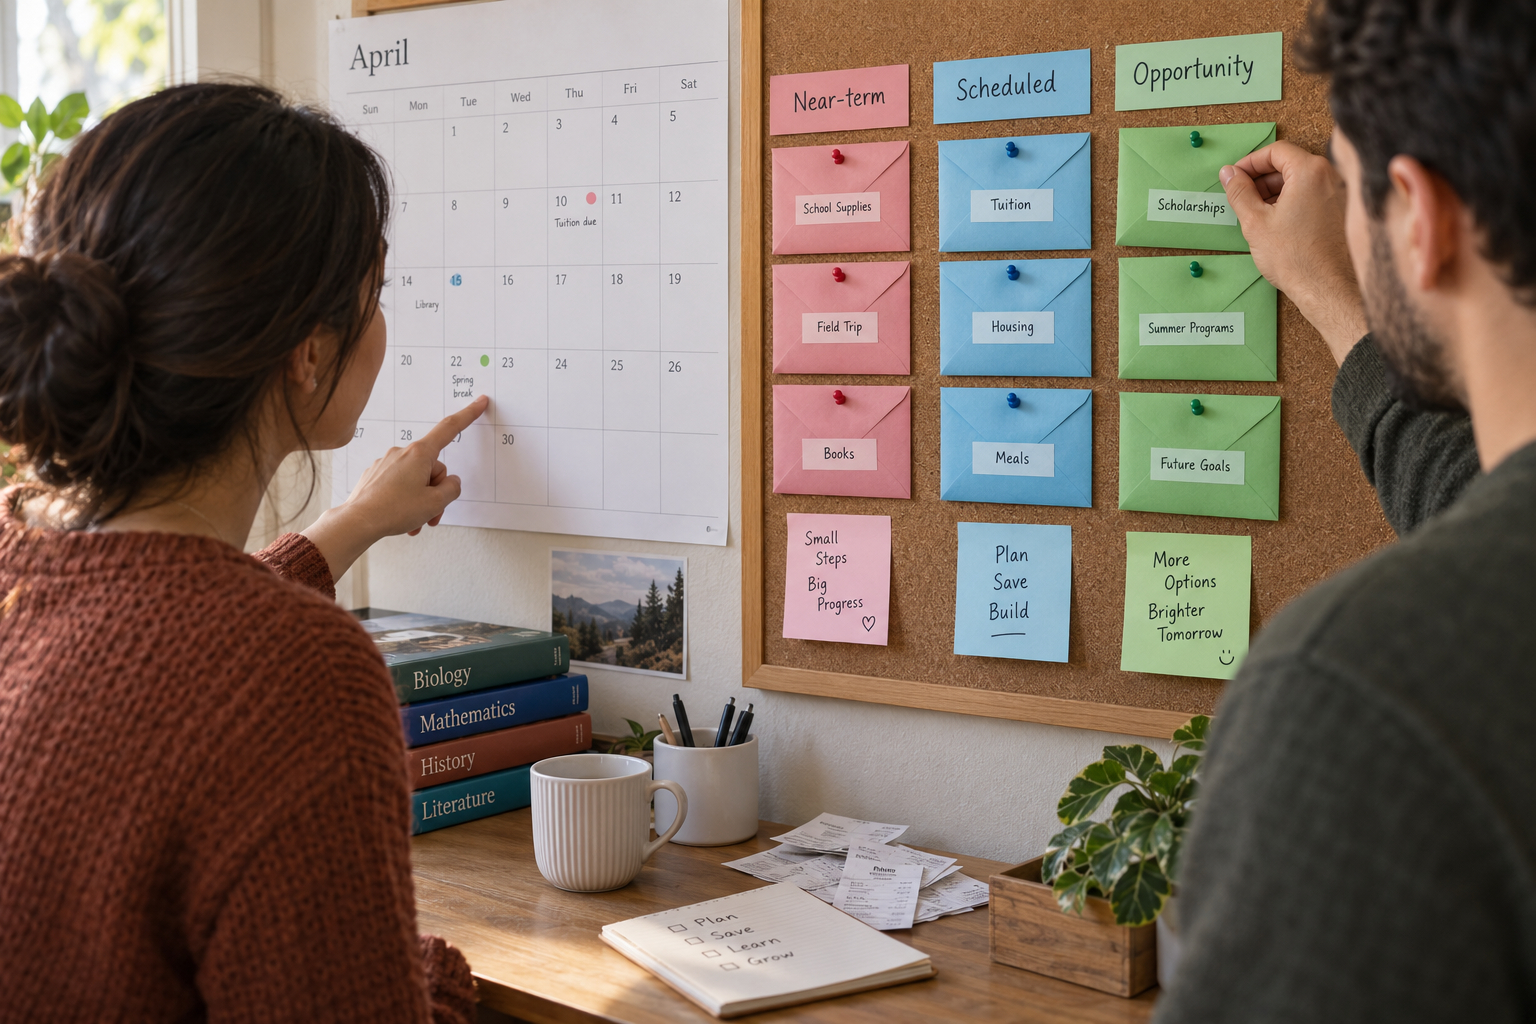
Managing education expenses requires a blend of foresight, structure, and flexibility. Households and individuals benefit from breaking costs into clear categories and aligning them with cash flow. A practical approach reduces stress while keeping learning goals on track. This article outlines steps to assess costs, prioritize funding, create flexible buckets, and adjust over time.
Assessing Education Costs
Start by identifying recurring and one-off education expenses, including tuition, materials, exams, and incidental fees. Estimate realistic ranges rather than single numbers to capture variability in costs and timing. Use historical spending, school calendars, and provider invoices to ground your estimates. Tracking actual payments for a year will quickly reveal patterns and irregular pressures.
- Tuition and enrollment fees
- Books, supplies, and equipment
- Exams, travel, and incidental costs
Translating those estimates into a schedule makes budgeting actionable. With categorized numbers you can experiment with funding strategies.
Prioritizing and Timing Funds
Once costs are mapped, prioritize based on deadlines, impact, and replaceability. Essential fees and deadlines take precedence, while optional courses or conferences can be scheduled when funds allow. Consider timing income streams, scholarships, or employer support to match payment windows. Short-term savings vehicles differ from long-range accounts, so align the instrument with the timing.
Prioritization prevents last-minute borrowing and missed opportunities. Clear rules about what to fund first simplify decisions.
Building Flexible Funding Buckets
Create several purpose-driven buckets: near-term cash, scheduled savings, and opportunity funds for unexpected learning chances. Near-term cash covers expenses within 12 months and should be liquid; scheduled savings can use recurring transfers timed to billing cycles. Opportunity funds stay smaller but available for short-notice workshops or unexpected fees. This layered setup balances liquidity with growth potential.
- Near-term cash: liquid, for bills within the year
- Scheduled savings: recurring transfers for known milestones
- Opportunity fund: flexible money for ad hoc learning
Automate transfers where possible to reduce decision fatigue. Review contribution rates after major life changes.
Managing Ongoing Adjustments
Set a routine review—quarterly or annual—to compare estimates against actual spending and update priorities. Rebalance buckets as needed: move surplus from closed items to future goals, or pause contributions during tight months. Keep an emergency buffer separate so education savings aren’t raided for unrelated crises. Communication among household members about funding choices keeps plans realistic and shared.
Small, regular adjustments prevent surprises and protect long-term learning goals. Treat the plan as living, not fixed.
Conclusion
Planning education expenses is a practical exercise in allocation, timing, and flexibility. By assessing costs, prioritizing payments, creating layered funding buckets, and reviewing regularly you reduce stress and keep options open. A disciplined, adaptable system supports learning without destabilizing household finances.
Related Articles
Recent Posts

Calendar-First Approach to Managing Recurring Education Expenses
Creating Durable Household Systems for Education Funding
Developing Transferable Note-Taking Frameworks for Learners
Helping Students Design Personal Learning Dashboards for Growth
Helping Students Craft Sustainable Independent Study Systems


