Managing education expenses requires a structured approach that aligns priorities with household cash flow. Without a clear system, costs for courses, certifications, or continuing education can grow unpredictably and strain other goals. A sustainable framework reduces stress by defining rules for when to invest, pause, or pursue lower-cost alternatives. The steps below offer a practical way to organize funds, set decision criteria, and keep learning investments purposeful.
Assess Current Commitments
Begin by listing all upcoming and recurring education costs for the next one to three years, including tuition, materials, subscriptions, and travel. Estimate timing and amounts so you can see peaks and gaps in demand on cash flow. Categorize each item by priority: essential skill, career advancement, personal interest, or optional. This inventory creates visibility and prevents surprises when multiple opportunities appear at once.
Once commitments are mapped, identify which costs can be deferred or reduced and which require immediate funding. That clarity lets you prioritize payments without sidelining necessary expenses. It also helps determine whether additional savings or one-time reallocations are needed.
Create Tiered Funding Rules
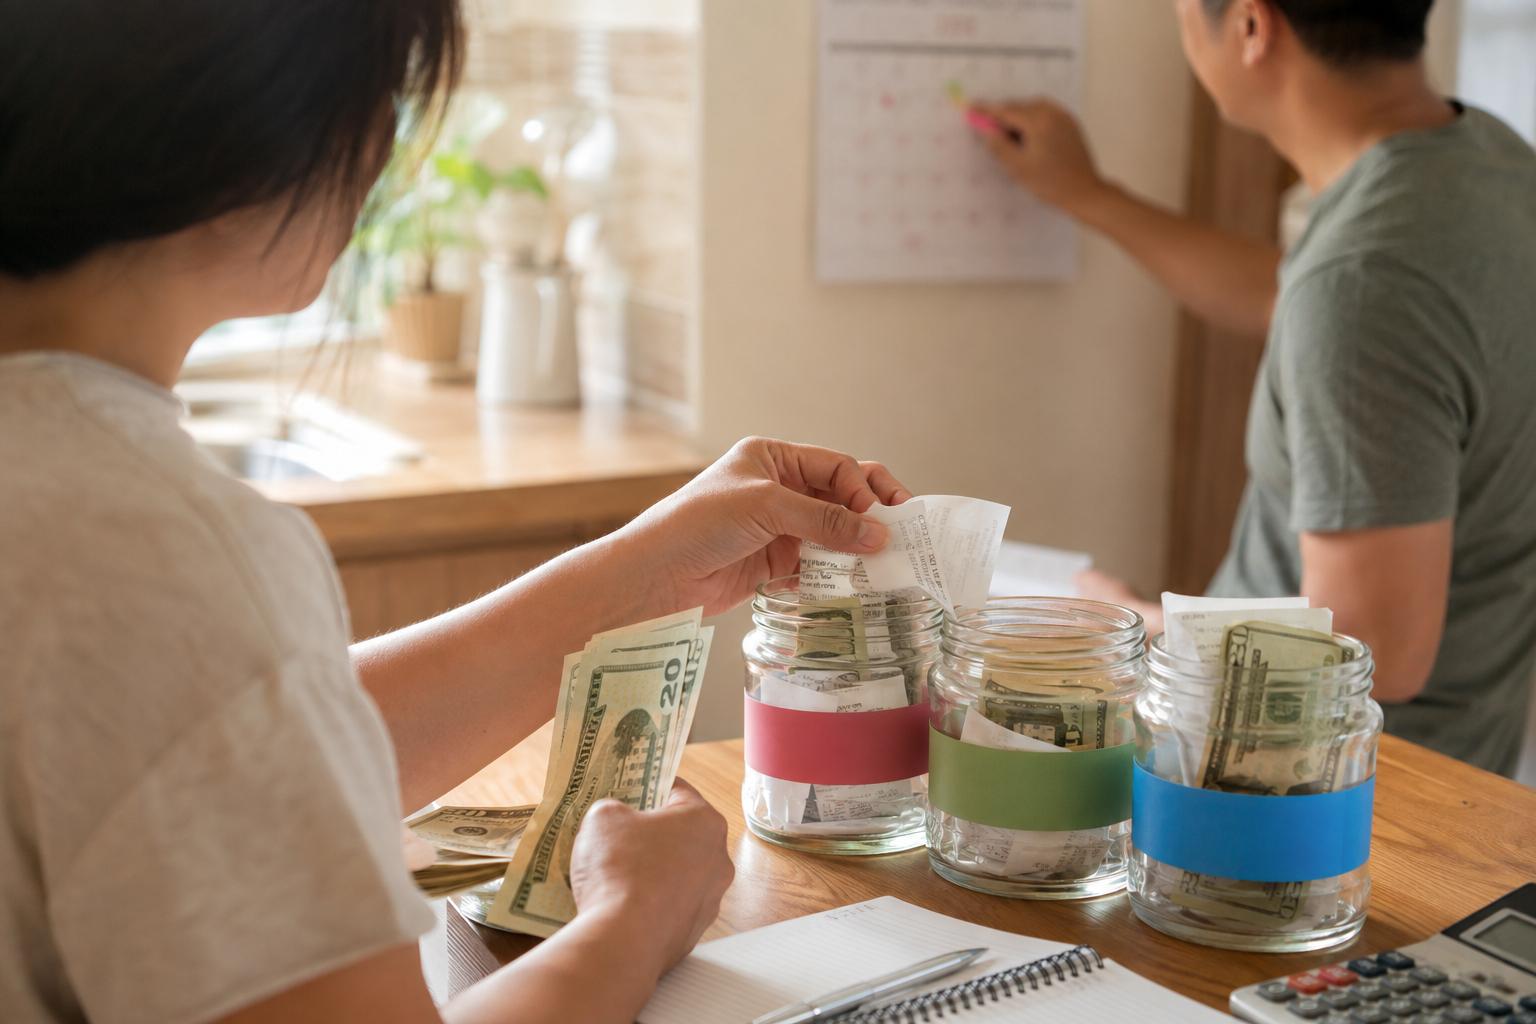
Design a simple tiered funding structure to match different types of education spending. A core fund covers required or time-sensitive learning; a development fund supports career-building opportunities; and an opportunity fund handles short-term certifications and experiments. Assign straightforward rules for each tier, such as target balances, contribution rates, or the percentage of windfalls that flow into each bucket.
- Core fund: reserve for mandatory or high-impact programs.
- Development fund: steady monthly contributions for planned growth.
- Opportunity fund: small flexible pool for trials and short courses.
Clear tiers reduce decision friction and make it easier to say yes when funding exists and no when it does not. They also simplify communication within the household about who pays for what.
Decision Rules and Timing
Set explicit decision rules that guide when to proceed with an expense: minimum fund thresholds, priority rankings, and evidence of expected return or personal value. Include pause triggers, such as an unexpected household expense or drop in income, and define acceptable alternatives like free resources or delayed enrollment. A written checklist speeds decisions and prevents emotional overspending around enticing offers.
Timing matters: align contributions with your billing cycles and schedule regular checkpoints to avoid last-minute borrowing. When a choice is uncertain, use trial periods or low-cost options to test value before committing significant funds.
Review and Adjust Regularly
Conduct quarterly or semiannual reviews of both fund balances and learning outcomes to ensure the system remains relevant. Track which investments delivered value and which did not, then reallocate future contributions accordingly. Small, regular adjustments keep funding rules responsive to changing household priorities and career shifts.
Involve household members in reviews to maintain shared understanding and support. Over time, consistent monitoring will make education spending predictable and sustainable without sacrificing meaningful opportunities.
Conclusion
Building a simple, tiered system makes education expenses manageable and aligned with long-term goals. Regular reviews and clear decision rules reduce friction and prevent unnecessary spending. With a few straightforward rules, learning investments become deliberate and sustainable.