Adopting a calendar-first approach turns irregular education costs into predictable, scheduled actions. By anchoring payments and savings to dates you already track, households reduce surprise pressure. This method emphasizes timing, simple rules, and periodic review to keep decisions consistent. The result is a low-friction routine that aligns learning investments with everyday cash flow.
Why a calendar-first approach works
Linking education expenses to the calendar leverages existing habits and systems most people already use. It reduces cognitive load by shifting choices from ad hoc decisions to pre-set actions. When bills, tuition payments, and course registrations map to monthly or quarterly reminders, it becomes easier to prioritize and avoid last-minute borrowing. Predictable timing also makes it simpler to communicate plans within a household and coordinate who pays when.
Using dates as an organizing principle reveals patterns in expense timing and frequency. Over a few cycles you can spot clusters and smooth them out with small adjustments.
How to set up your calendar system
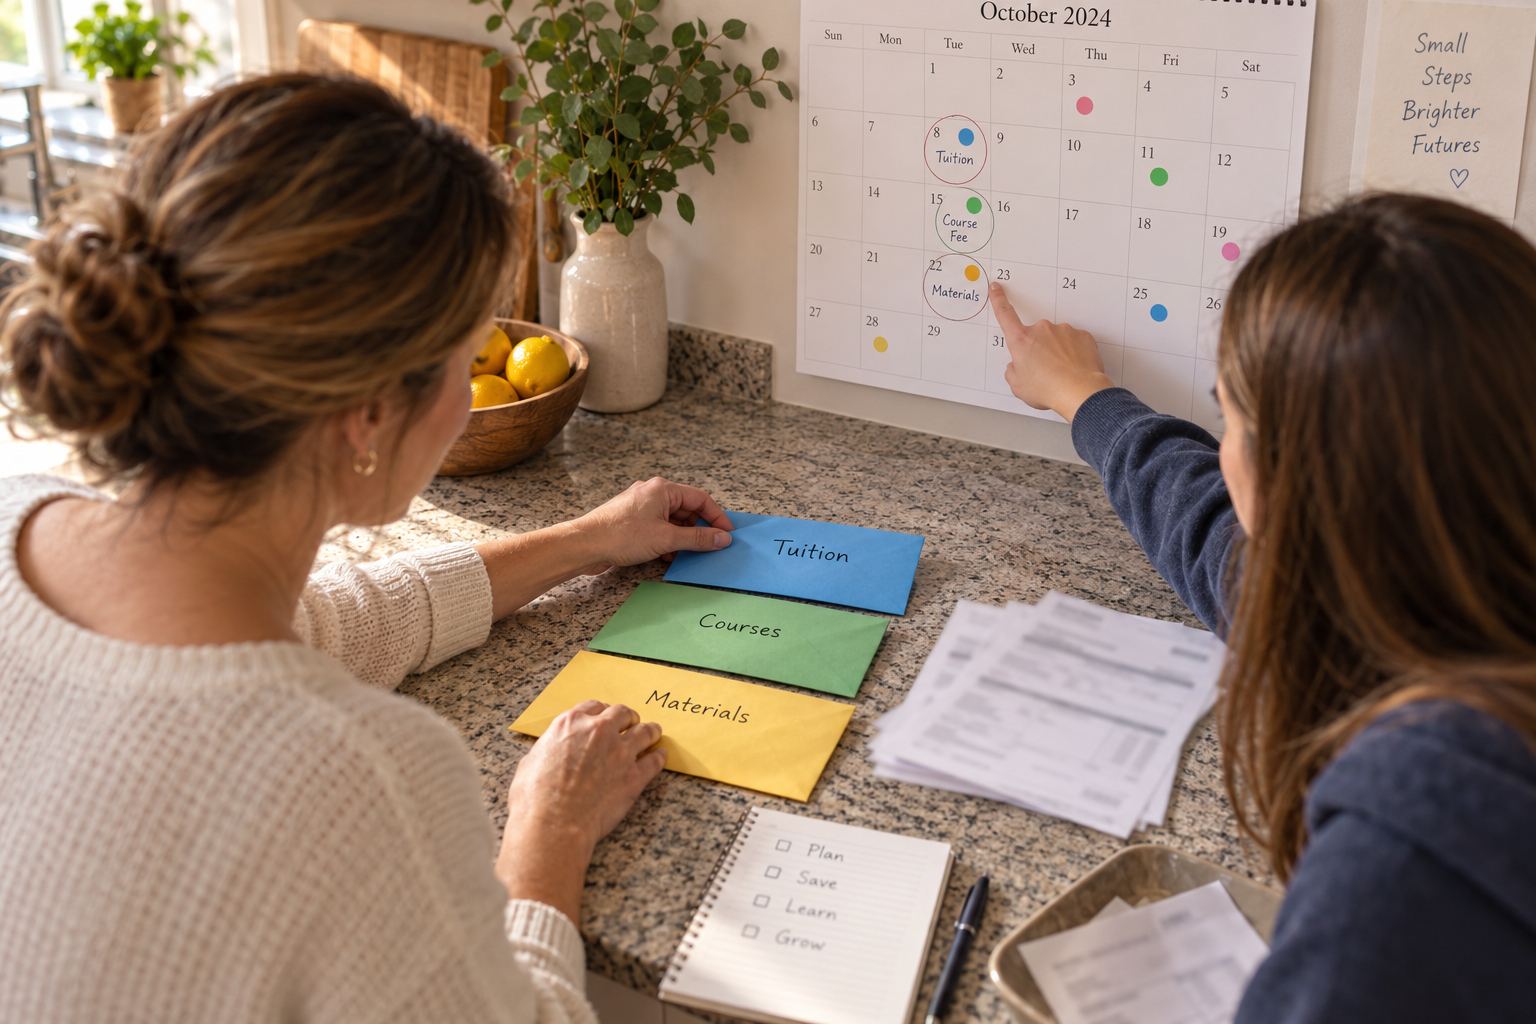
Start by listing every recurring or expected education expense and its typical timing, then add those dates to a shared calendar. Create simple rules: for example, move savings transfers two weeks before major tuition deadlines or split annual costs into monthly allocations. Automate transfers where possible and set reminders for decision points rather than every transaction. Keep one view that shows both payments and savings actions so the full impact on cash flow is visible at a glance.
- Assign responsibilities: who schedules, who approves, who transfers.
- Choose a cadence: monthly, quarterly, or aligned with paychecks.
With this setup, the calendar becomes both a planning tool and an operational checklist for education spending.
Managing irregular costs and adjustments
Not every education expense fits a neat schedule, so build predictable buffers and contingency slots into your calendar. Reserve one or two flexible line items per quarter for unexpected workshops, materials, or one-off training. When a new cost appears, slot it into the nearest planning period and evaluate trade-offs using pre-established priority criteria. Periodic reviews, ideally quarterly, let you reallocate buffer funds without making rushed choices.
Keeping a short decision checklist on the calendar reduces friction when adjustments are required and preserves overall predictability.
Conclusion
Making the calendar the control center transforms education expenses from surprises into scheduled actions. A few simple rules, automation, and periodic review keep spending aligned with cash flow and priorities. This approach is scalable and easy to maintain for most households seeking steadier education funding.