Managing education expenses can feel overwhelming at times, especially when multiple goals compete for the same resources. A clear, repeatable approach reduces stress and avoids last-minute compromises. This article outlines practical steps to structure household education funding around timing, priorities, and buffers. It focuses on assessable choices rather than one-size-fits-all prescriptions. Use these ideas to create a flexible plan that fits your household rhythm.
Assess Current Needs and Cash Flow
Start by creating an inventory of upcoming education costs and a snapshot of current cash flow. Include tuition, materials, subscriptions, transport, and informal courses so estimates reflect real obligations. Estimate timing and likely amounts for the next one to three years to identify seasonal peaks and potential funding gaps. Clear, itemized data makes prioritization and funding decisions more objective and less reactive.
- Short-term costs: within 12 months.
- Planned commitments: 1–3 years out.
- Optional or aspirational learning goals.
Label items by both urgency and impact so your plan distinguishes essentials from nice-to-haves. That clarity helps when deciding which expenses to fund first.
Design Tiered Funding Buckets
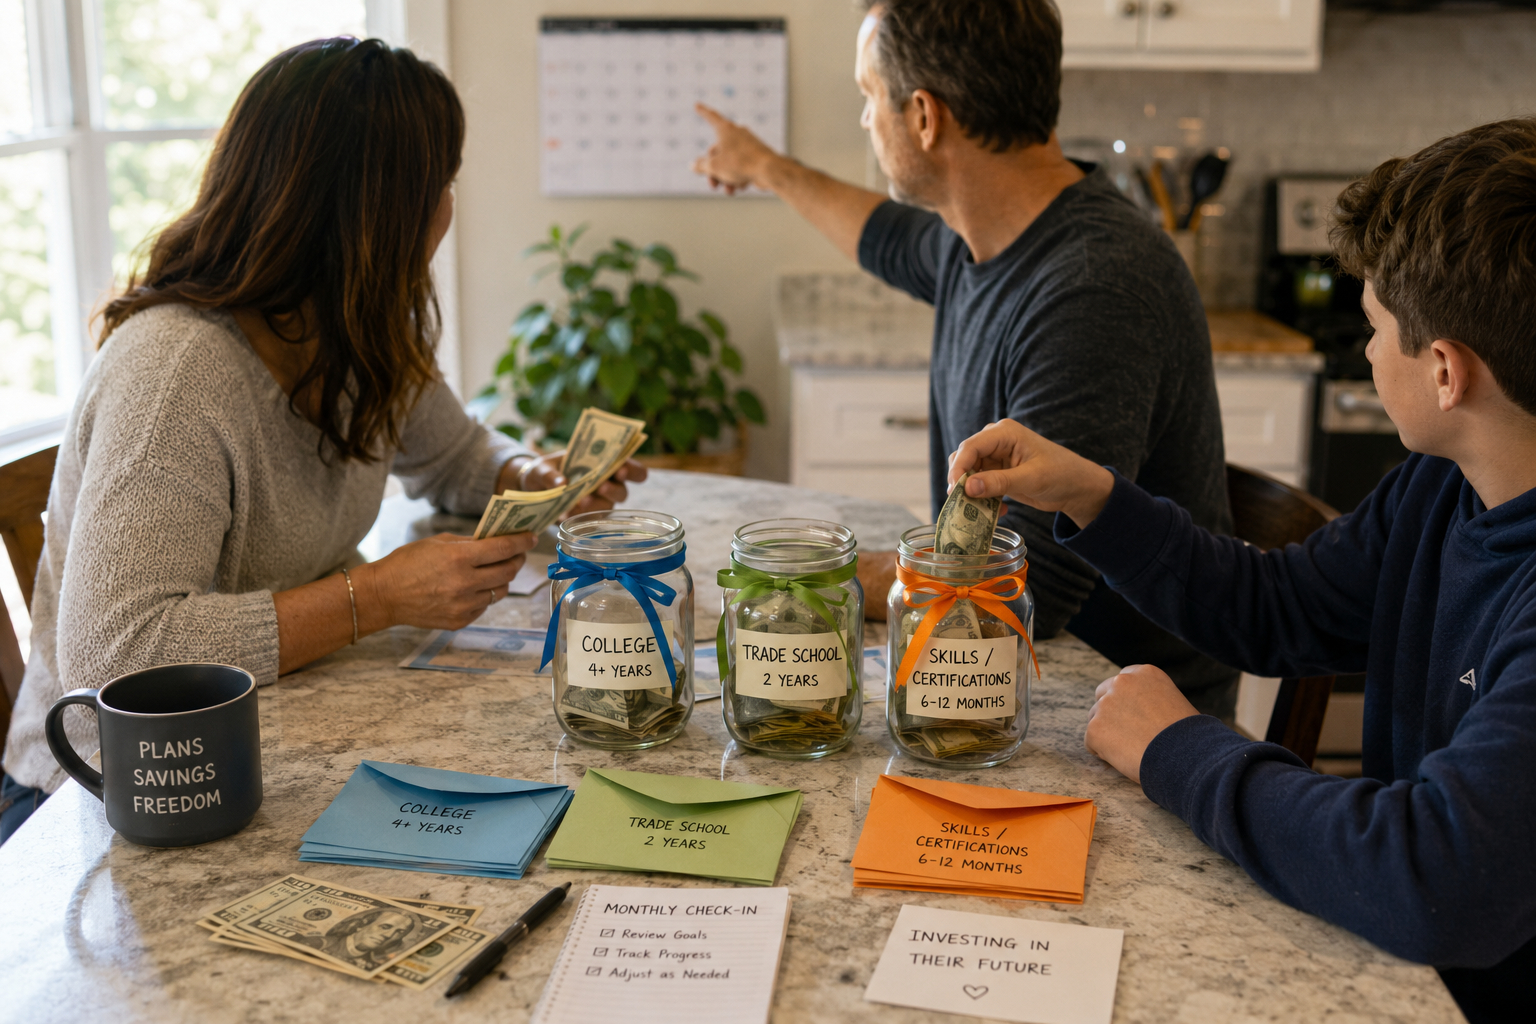
Organize money into three simple buckets: essentials, scheduled investments, and opportunity funds. Essentials cover unavoidable costs tied to enrollment or core curriculum and should be integrated with the main household budget. Scheduled investments are contributions timed for known future payments, while opportunity funds let you capitalize on ad hoc courses without derailing essentials. This tiered structure balances predictability with flexibility.
- Essentials: bills and required fees.
- Scheduled: term or semester contributions.
- Opportunity: short courses, conferences, or electives.
Set explicit rules for using each bucket so decisions are faster and less emotional. Rules also make it easier to replenish funds after withdrawals.
Monitor, Review, and Adjust
Implement a simple cadence for review, such as monthly check-ins and term-by-term planning updates. Track actual spending against each bucket and adjust contributions when income or priorities change. Maintain a small buffer within essentials to handle price increases or minor emergencies without tapping growth funds. Use a basic spreadsheet or budgeting tool to record changes and to keep everyone informed.
Hold a quarterly review to confirm priorities and reallocate as needed. Small, consistent adjustments keep the system resilient and aligned with evolving goals.
Conclusion
A structured plan converts sporadic education spending into deliberate choices. Start with clear data, assign funds to defined buckets, and review regularly to stay on track. Over time this approach reduces stress and preserves broader household objectives.