Handling education expenses calls for a clear, repeatable approach that fits household priorities and cash flow. A practical spending plan turns uncertain costs into manageable steps and reduces last-minute stress. This article outlines core choices — prioritization, timing, and simple funding rules — that help families make consistent decisions. The goal is sensible structures you can review periodically without overcomplicating day-to-day finances.
Maintaining a steady process is more important than perfect forecasting; small, reliable habits compound into predictable outcomes over time.
Why a structured plan matters
A structured plan gives you a framework to say yes to the right education opportunities and say no to less-aligned requests. It clarifies which expenses are essential, which are optional, and how much risk you will accept. When household members understand the rules, decisions become less emotional and more consistent. That clarity also makes it easier to evaluate new opportunities against existing commitments.
Ultimately, structure protects both learning goals and overall financial stability by preventing surprise trade-offs and preserving flexibility for higher priorities.
Assess priorities, timing, and funding sources
Start by listing potential education costs and grouping them by when they will be needed and how critical they are to goals. Identify reliable funding sources and which costs justify using them. Consider short-term cash, medium-term savings, scholarships or grants, and loan options as distinct resources to deploy strategically. Knowing the timing for each expense helps you smooth contributions across months or years.
- Short-term: emergency or immediate learning needs funded from cash flow.
- Medium-term: planned courses paid from reserved savings or staggered payments.
- Long-term: major certifications or degrees supported by targeted savings or financing.
Mapping needs to sources reduces the temptation to use one pot for all costs and preserves options when priorities shift.
Design funding buckets and simple rules
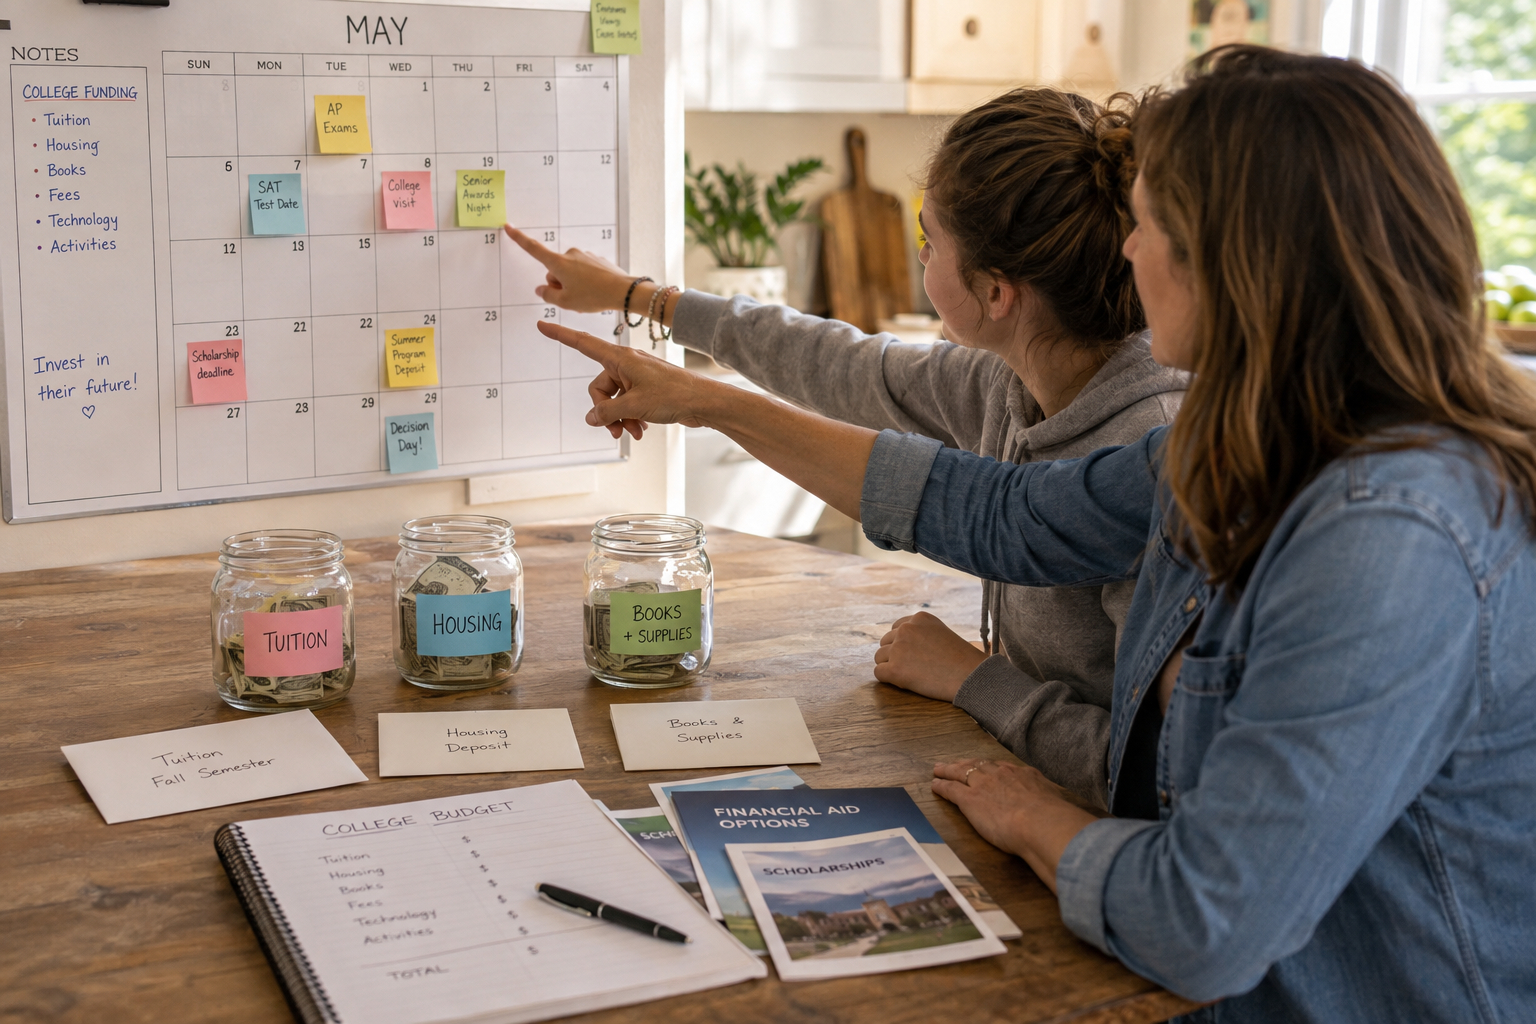
Create a few clear buckets with straightforward rules for when to use each one. Keep the system small: for example, essential development, optional enrichment, and contingency. Define triggers such as minimum balance thresholds, required outcomes, or advance approvals to spend from each bucket. Simple rules speed decisions and make the plan easier to follow for everyone involved.
Automate transfers where possible and document the rules so they remain consistent during busy periods or transitions.
Monitoring and iterative adjustments
Review the plan at regular intervals and after significant changes like a new job or a major program expense. Track actual spending versus plan and note recurring mismatches that suggest rule tweaks. Adjust contributions, reallocate buckets, or change priorities based on experience rather than emotion. Small quarterly reviews keep the plan aligned with changing household needs without creating a heavy administrative burden.
With routine monitoring you can learn what works and maintain resilience as circumstances evolve.
Conclusion
Build a compact plan that maps priorities, timing, and distinct funding sources. Use a few simple buckets and clear rules to guide decisions, and automate contributions when practical. Review regularly and adjust based on outcomes to keep education spending sustainable and aligned with household goals.