Household learning costs are often irregular but predictable when viewed through a framework. Establishing clear rules for when and how to fund courses, materials, and training helps reduce stress and avoid ad hoc decisions. A balanced approach links spending to priorities, timing, and available cash flow without creating rigid commitments. This article outlines practical steps to structure funds so learning fits your household rhythm.
Assess Your Learning Priorities
Start by listing the types of learning expenses your household faces and rank them by impact and urgency. Consider short-term needs like certificates, medium-term plans like degree programs, and occasional costs such as conferences or workshops. Assess who benefits from each expense and how it supports broader household goals, whether career advancement, hobby development, or family enrichment. That clarity will inform whether costs should be treated as essential, discretionary, or experimental.
Once priorities are set, assign a funding intent to each category: save, share, or delay. These simple rules turn priorities into decisions that are easy to execute when opportunities arise.
Create Tiered Education Funds
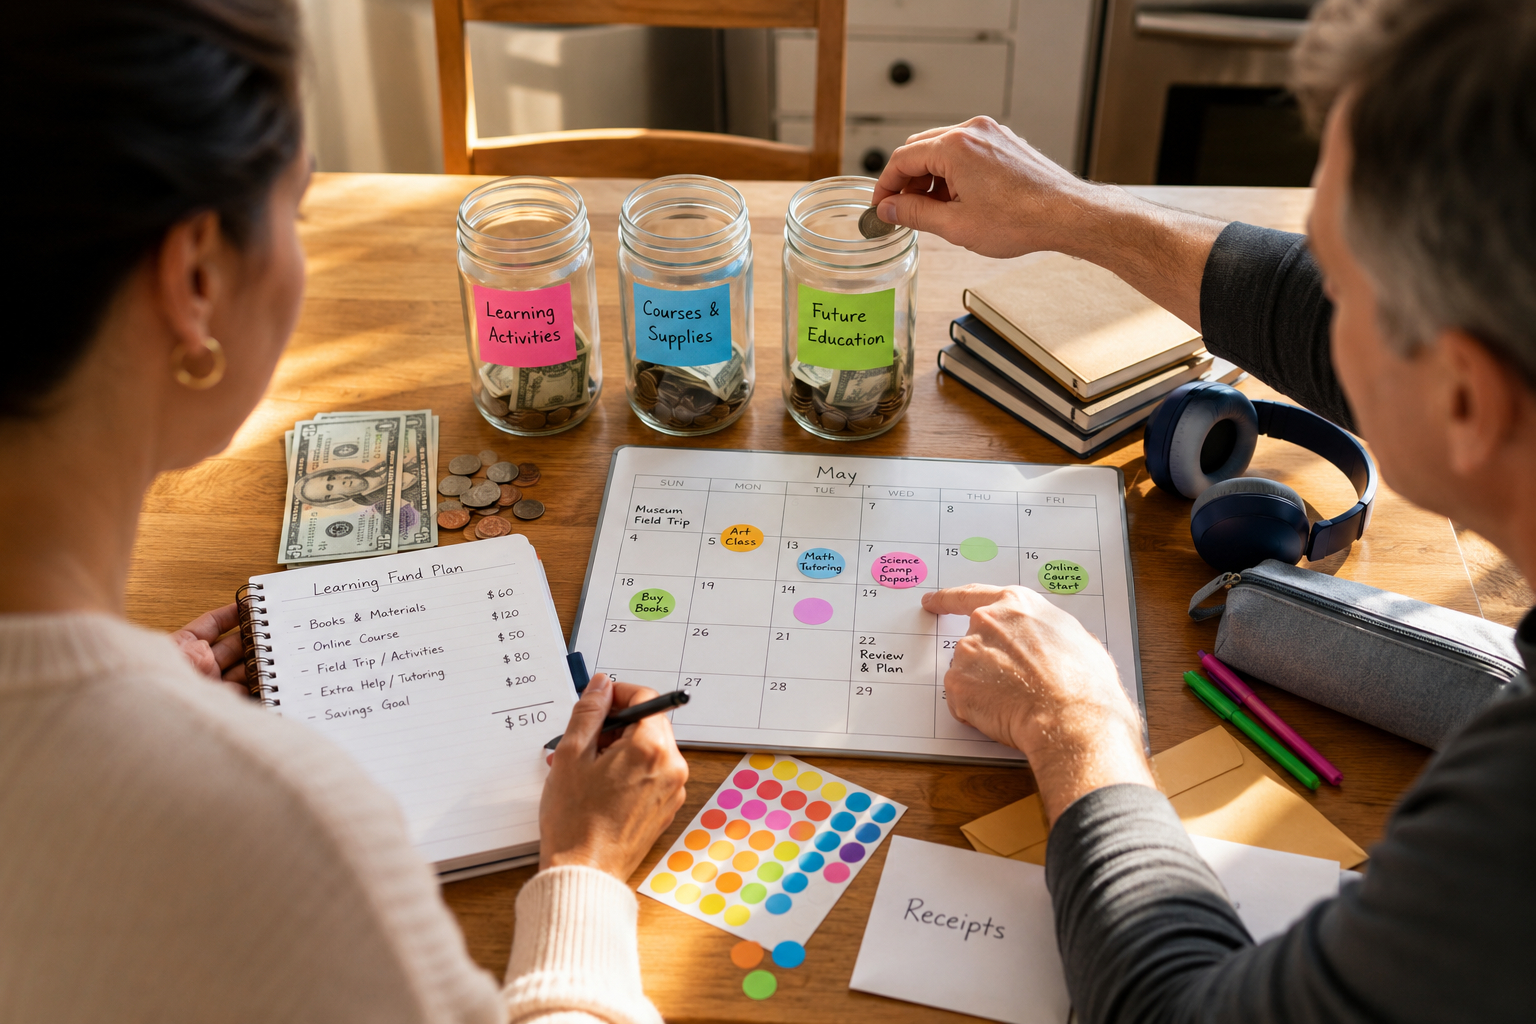
Design three complementary funds: an essentials fund for predictable, recurring costs; an opportunity fund for high-value, time-sensitive chances; and an exploration fund for small-scale learning experiments. The essentials fund covers subscriptions, mandatory fees, or ongoing classes and should align with your monthly budget cadence. The opportunity fund is larger and accessed for strategic investments such as degree tuition or professional credentials that significantly affect earnings or outcomes. The exploration fund is flexible and supports trying new skills without disrupting other budgets.
- Essentials: steady contributions timed with billing cycles.
- Opportunity: targeted savings for bigger commitments.
- Exploration: a low-barrier pool for trials and small expenses.
These tiers keep small purchases from eating into long-term learning investments and make trade-offs explicit when choices arise.
Monitor, Review, and Adjust
Set a regular review cadence—quarterly or biannually—to reconcile spending, measure outcomes, and adjust contributions. Track simple metrics such as cost per completed course, return on time invested, and alignment with household goals to inform future choices. Use automatic transfers to maintain discipline but leave room to reallocate funds when priorities change or unexpected needs appear. Communication and documented rules reduce friction and ensure that everyone in the household understands how decisions are made.
Consistent monitoring builds confidence and makes it easier to pause, scale, or accelerate learning investments as circumstances evolve.
Conclusion
Structuring household learning funds around priorities, timing, and clear rules reduces reactive spending and supports better outcomes. A three-tier system—essentials, opportunity, exploration—balances stability with flexibility and keeps learning aligned with household goals. Regular reviews and simple metrics ensure the funding approach stays relevant and sustainable.