Households face fluctuating education needs and irregular payment schedules, so a milestone-based funding approach helps keep plans manageable and focused. Breaking long-term learning goals into concrete milestones clarifies timing and cost estimates and reduces decision fatigue. This method supports prioritization when resources are limited and provides checkpoints to re-evaluate commitments. Implementing milestones with simple rules makes it easier to align education spending to broader household finances.
Set clear milestones
Start each plan by defining meaningful milestones tied to outcomes rather than vague goals. Examples include completing a certification, finishing a semester of coursework, or saving toward a tuition deposit; each milestone should have a target date and a rough budget. Assign priority levels so the household can choose which milestones proceed when money is tight. Clear milestones reduce emotional spending and make trade-offs more transparent.
Document the milestones in a shared place and review before committing funds. Small, intentional steps help keep the plan realistic.
Estimate costs and timing
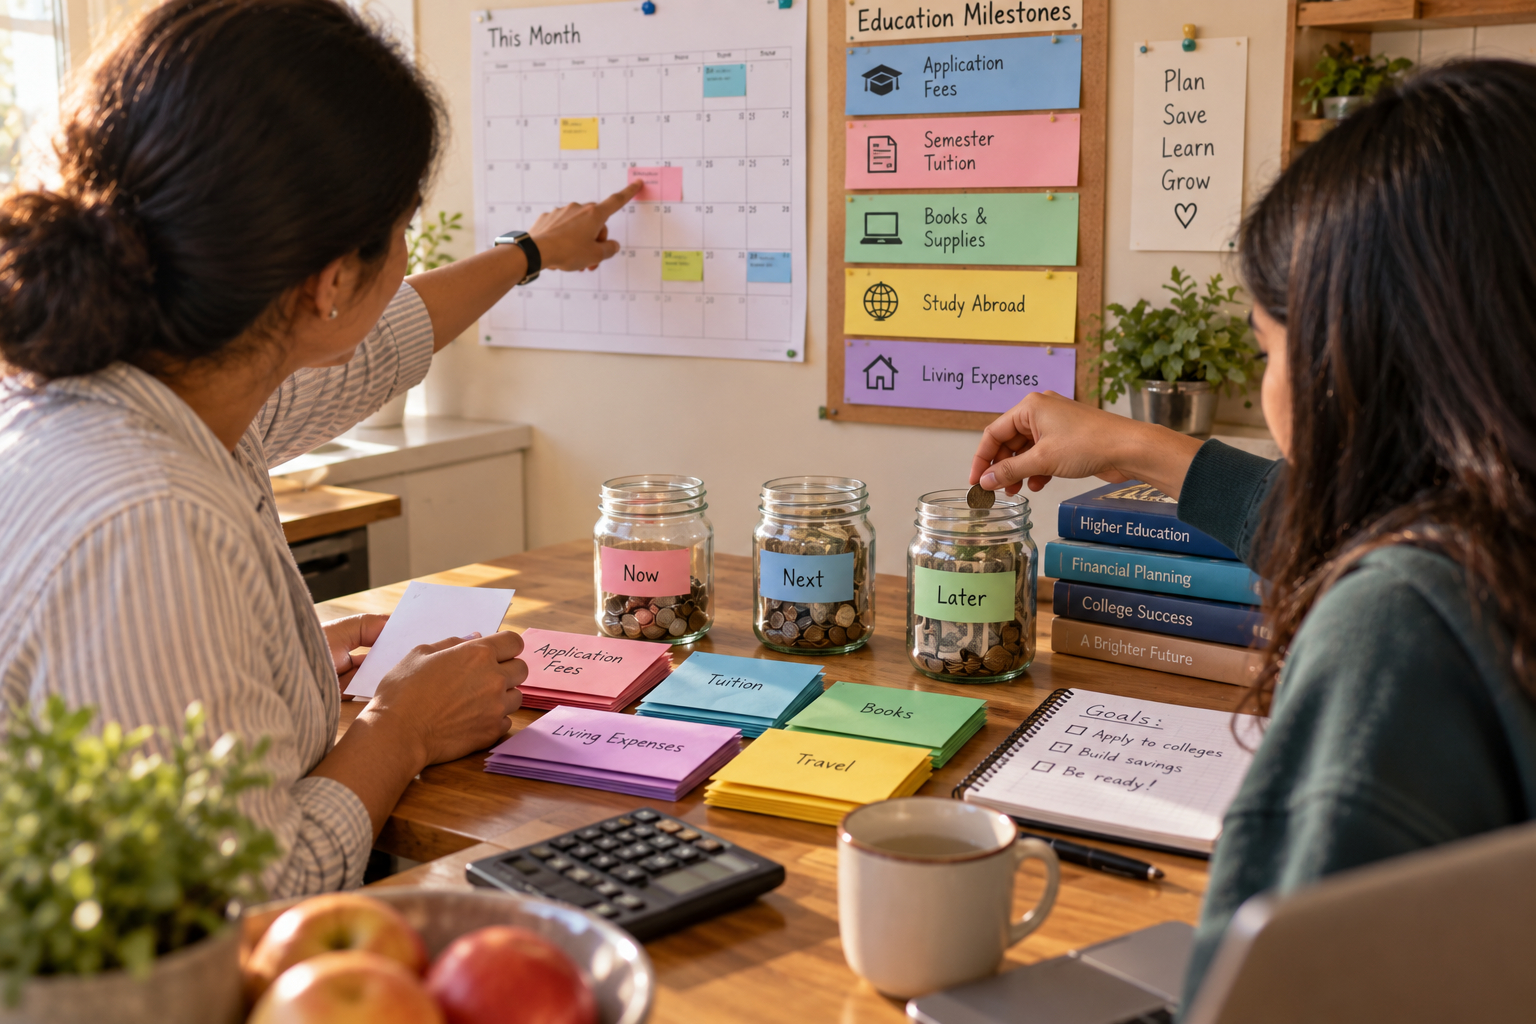
When estimating costs break each milestone into line items such as tuition, materials, travel, and opportunity cost. Use conservative estimates and round up to create a buffer for unexpected fees. Consider cash-flow timing: some items are one-off while others recur across months or years. Clear timing reduces surprises and helps match funding sources to needs.
Maintain a simple schedule that lists when each payment is due and the anticipated funding source. This schedule can be tied to the household calendar for reminders.
Align diverse funding sources
Match milestones to appropriate funding sources: emergency savings for short-term shortfalls, dedicated education savings for predictable costs, and income or financing for larger investments. Consider splitting costs across time to avoid relying on high-interest borrowing. Create rules that specify when to pause or postpone lower-priority milestones if funding gaps appear. Transparency about which account pays for what reduces confusion during tight months.
Label accounts and set simple transfer rules so money flows where it should. Periodic rebalancing keeps priorities aligned as circumstances change.
Create a review routine
Schedule regular checkpoints to compare progress against milestones, costs, and timing assumptions. At each review, adjust budgets, re-prioritize milestones, or extend timelines as needed. Use quantitative metrics such as months of funding saved and qualitative check-ins about value and fit. Reviews prevent small misalignments from turning into last-minute crises.
Keep reviews short and focused to maintain momentum. Involve household members so decisions are shared and realistic.
Conclusion
Milestone-based funding turns vague intentions into practical actions that households can manage alongside other priorities. By estimating costs, matching funding sources, and reviewing regularly, families create a resilient system. Start small and iterate — consistency creates stability over time.