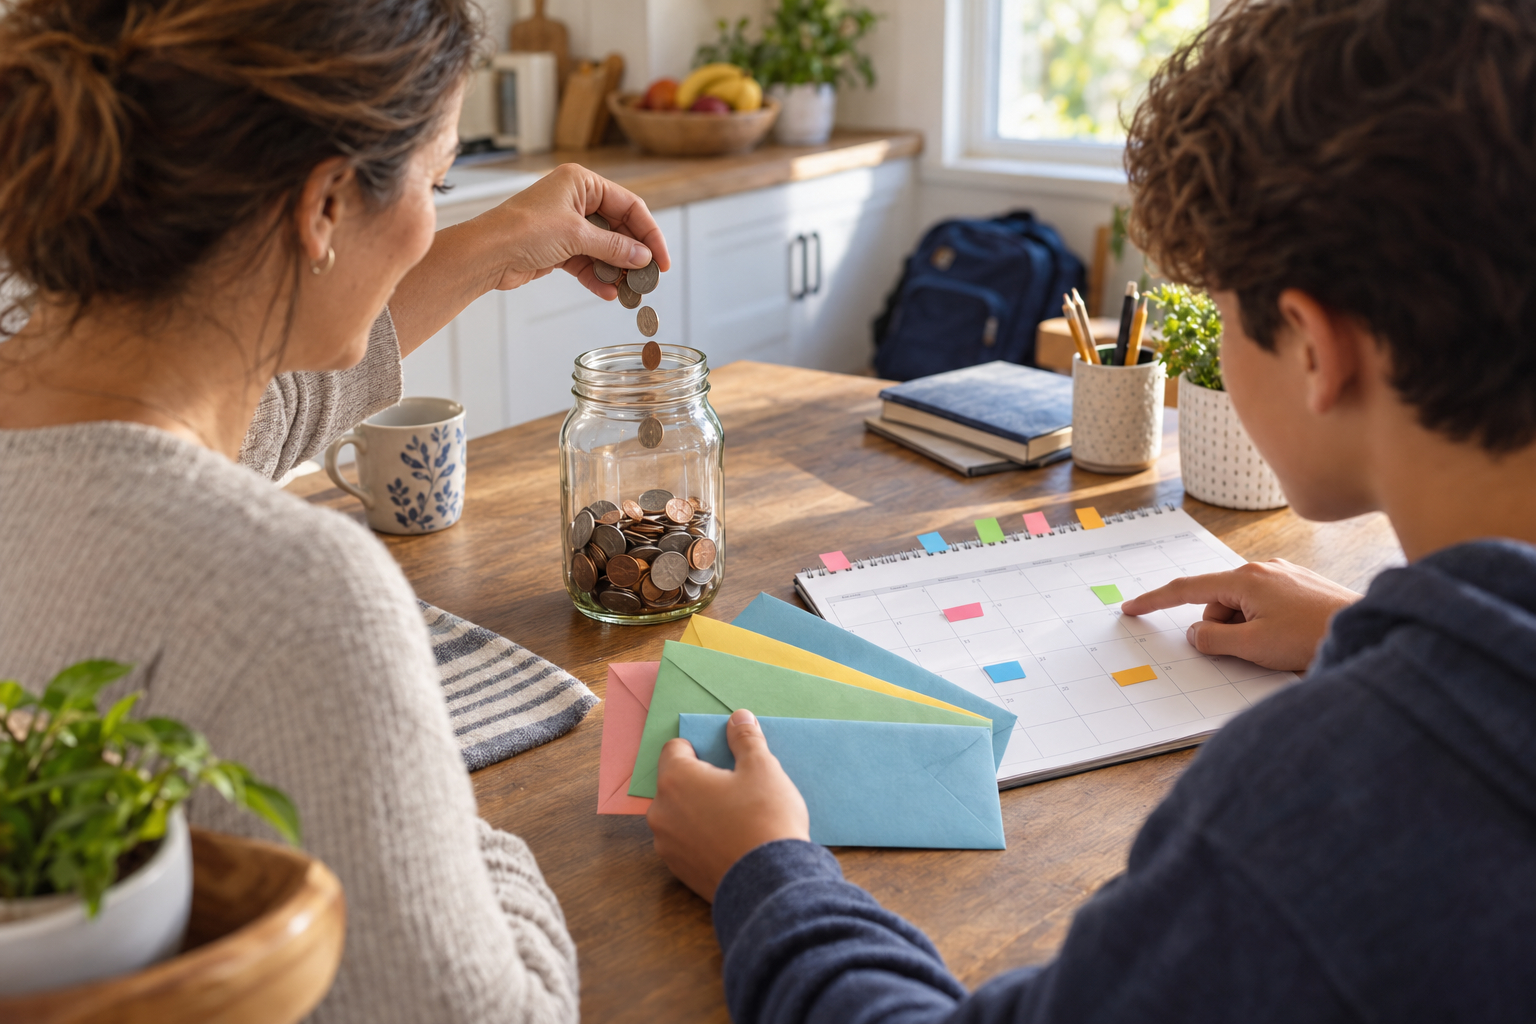
Unexpected tuition, course fees, or supplies can strain a household budget. Consistent, small habits reduce stress and keep learning on track. This article outlines practical everyday actions families can use to smooth education spending. The focus is on predictable moves that fit regular cash flow.
Start With Small, Predictable Allocations
Rather than waiting for large bills, set aside a modest fixed amount each pay period specifically for education. Even an amount that feels minor compounds over time and creates a buffer for courses or materials. Automating transfers to a dedicated account prevents ad hoc spending. This steady approach reduces reliance on credit or last-minute adjustments.
Treat the allocation like an ongoing subscription rather than a spontaneous expense. That mindset shifts decisions from reactive to planned.
Use a Tiered Priority List
Not every learning expense carries equal weight, so rank needs by urgency and long-term benefit. Core costs such as compulsory fees sit at the top, while optional workshops or premium materials sit lower. Assign funding sources or thresholds for each tier to guide choices when money is tight. This keeps essential learning supported without overcommitting to lower-impact items.
A simple three-tier list is often enough: must-pay, nice-to-have, and discretionary. Reviewing it quarterly helps match spending to evolving goals.
Monitor and Adjust Seasonally
Education costs often follow seasonal patterns—registrations, semester starts, or certification renewals. Track expected outflows on a simple calendar so you can redistribute savings ahead of peak months. Regularly reviewing spending trends reveals small leaks and opportunities to reallocate. Adjust allocations up or down based on actual needs rather than emotion.
Seasonal forecasting prevents last-minute scrambling and smooths cash flow. It also makes it easier to identify when to pause or accelerate investments.
Tools and Routines to Make It Stick
Use straightforward tools like dedicated savings accounts, calendar reminders, and a lightweight spreadsheet to keep tabs on progress. Mobile alerts for transfers and spending thresholds help maintain discipline without heavy administration. Involve family members in simple budgeting decisions so expectations are clear. Regular routines reduce friction and make saving a normal part of household finance.
Small automation and clear rules remove guesswork from education spending. Over time these routines build resilience against cost surprises.
Conclusion
Everyday habits, small allocations, and clear priorities together make education expenses manageable. The goal is steady, predictable behavior rather than dramatic shortcuts. Start with one habit today and build gradually for long-term stability.
Related Articles
Recent Posts

Synchronizing Education Funds with Monthly Income Cycles
Practical Roadmap for Household Education Expense Management
Designing Compact Choice Menus to Foster Student Decision-Making
Teaching Students to Sequence Tasks for Deeper Engagement
Practical Classroom Methods for Teaching Strategic Study Prioritization


