Deciding when and how to pay for education can be a recurring source of stress for households with competing priorities. Simple, repeatable rules reduce decision friction and keep spending aligned with longer-term goals and available resources. This article lays out practical everyday rules to prioritize, fund, and review education expenses in a way that is both realistic and repeatable. Following these steps helps you make choices that balance likely benefit, timing, and household cash flow without constant debate.
Set clear priorities and funding criteria
Begin by defining which types of learning matter most to your household and why, whether that is credentialing, upskilling for income, or enrichment for personal development. Create a short ranked list that ties each item to measurable goals, such as career advancement potential, enrollment deadlines, or required prerequisites. For each priority assign a funding rule: full support, partial subsidy, or self-funded pay-as-you-go, and specify any documentation needed to access funds. These concrete criteria remove ambiguity and make it easier to compare opportunities when multiple requests arise.
Share the list and rules with household members so expectations are clear and consistent. Make updating priorities a regular appointment when life changes affect goals or finances.
Layer funding by timing and impact
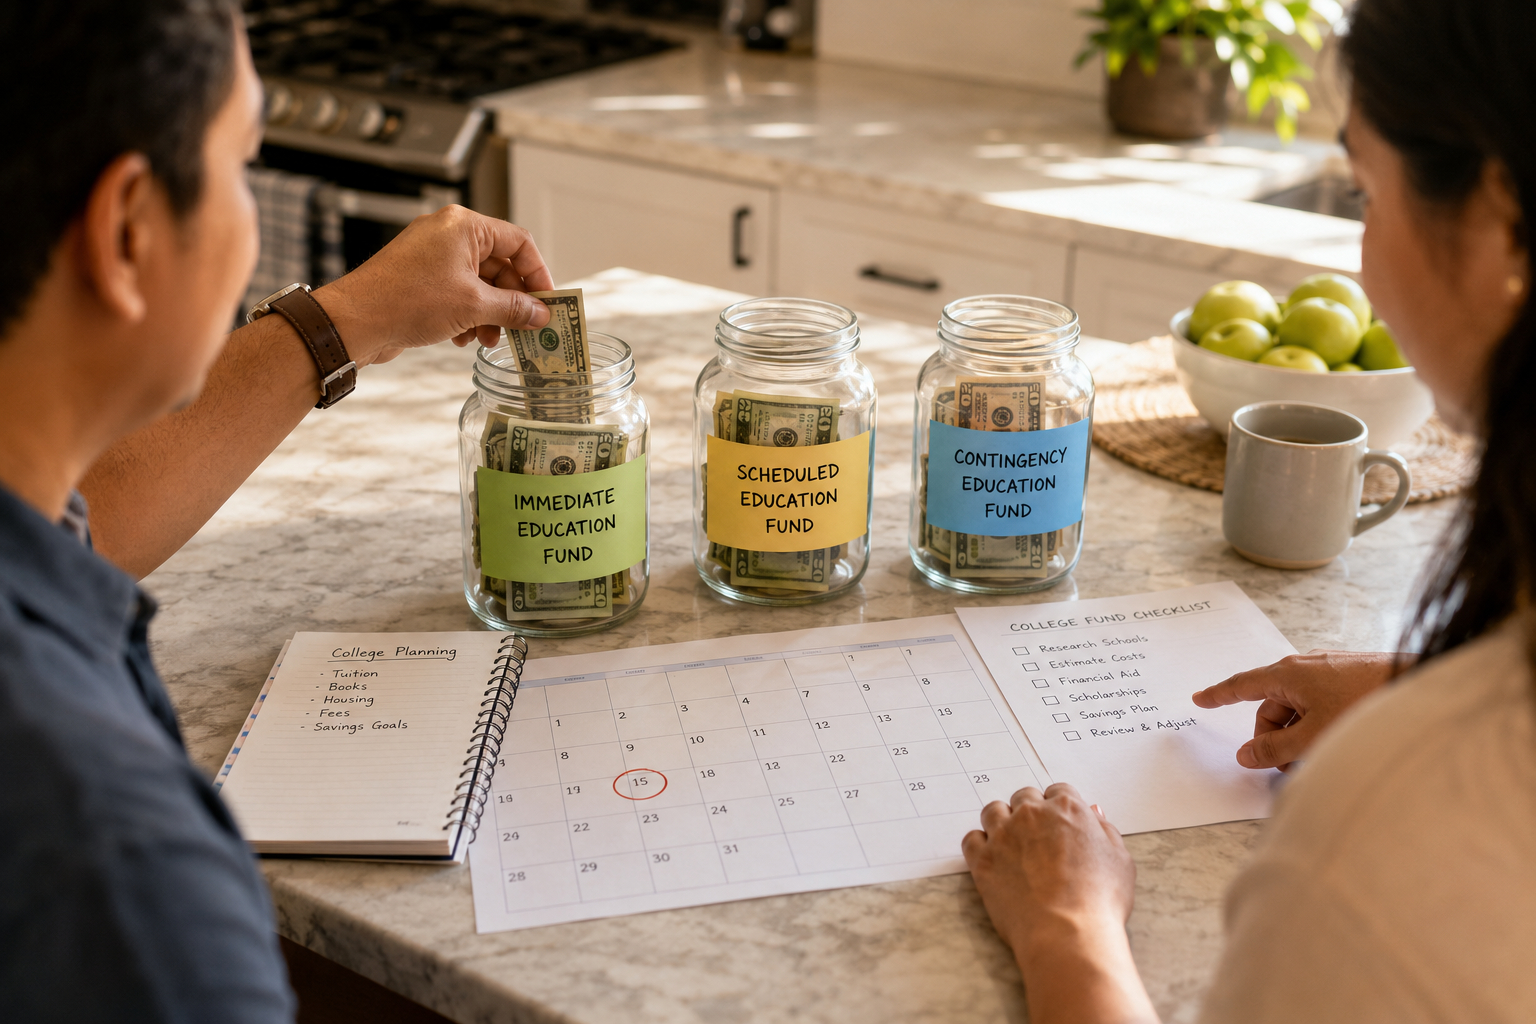
Organize education funds into tiers that reflect both when the expense will occur and the expected return on investment, so short-term opportunities and long-term plans do not compete for the same dollars. Maintain an immediate usage bucket for upcoming courses that offer quick, measurable benefits, a scheduled savings bucket for planned long-term programs, and a modest contingency reserve for unforeseen openings or price changes. Assign contribution rates, target balances, and review dates for each tier so progress is trackable and predictable. This structure prevents large, last-minute withdrawals from emergency funds and aligns contributions with the timing of benefits.
- Immediate bucket: funded from monthly cash flow for near-term commitments.
- Scheduled bucket: systematic savings for larger, planned programs.
- Contingency reserve: small cushion for opportunistic or timing shifts.
By matching funding to timing and impact, you preserve financial stability while allowing flexibility for worthwhile opportunities. Regularly test whether contribution rates need modest adjustments as priorities evolve.
Use triggers, reviews and simple governance
Adopt objective triggers that authorize funding, such as confirmation of enrollment, verified job outcomes, or completion of prerequisite milestones, to prevent ad hoc spending. Pair those triggers with a light quarterly review where progress, budget impacts, and shifting priorities are discussed and recorded, enabling adjustments without friction. Establish a simple governance rule for larger expenditures—perhaps a two-person sign-off or a predefined approval threshold—so big decisions get a quick, impartial check. These practices reduce emotion-driven choices and keep education spending aligned to agreed household aims.
- Example trigger: documented employer tuition assistance matching an approved program.
- Example governance: any expense above a set dollar amount requires joint approval.
Keep records in a shared document so decisions and rationales are easy to reference in future discussions. Over time this history improves consistency and trust.
Conclusion
Everyday rules make education spending predictable, fair, and aligned with household priorities. They reduce emotional strain, protect broader financial stability, and make it easier to seize high-value opportunities without derailing other goals. Start with a simple set of priorities, a layered funding plan, and light governance, then refine the system as you learn.