Managing education expenses requires clear rules and consistent routines to avoid last-minute stress. Small, repeatable policies reduce decision fatigue and make funding more predictable against other household commitments. This article presents a practical framework that combines explicit policies, funding tiers, and scheduled reviews to keep costs manageable. The approach is adaptable and intended to work across different household cash-flow patterns.
Set Clear Household Policies
Start by defining a small set of written policies that guide who pays for what, which priorities come first, and when to pause or re-evaluate a commitment.
- Decide eligibility: which courses, certifications, or programs qualify for shared funding.
- Define contribution limits and acceptable financing options.
- Establish decision points when expenses exceed preset thresholds.
Having clear rules shortens discussions and makes allocation fairer, while also protecting emergency and savings buffers from mission creep.
Create Funding Tiers and Timing
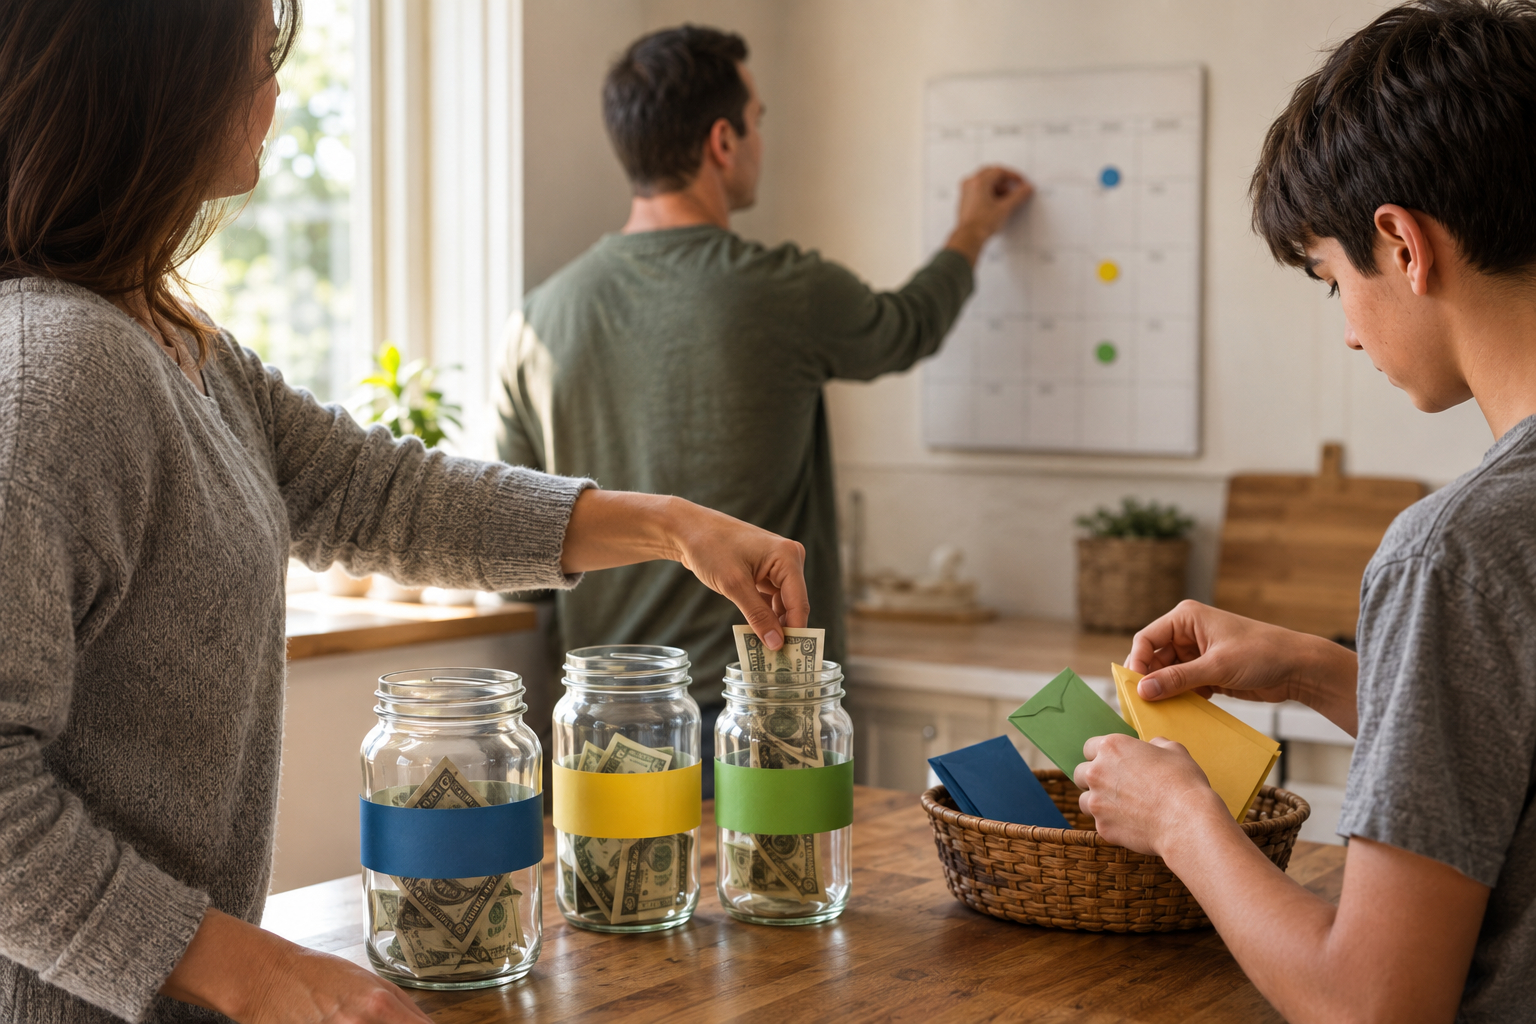
Organize education spending into tiers — immediate small learning purchases, planned short-term investments, and larger long-term commitments — and assign separate funding paths for each tier.
- Tier 1: Day-to-day or low-cost courses covered by a monthly learning allowance.
- Tier 2: Planned short-term programs funded through a designated education savings account.
- Tier 3: Major multi-term investments with a combination of savings and planned borrowing if needed.
Mapping timing to tiers reduces surprises and makes it easier to prioritize when multiple needs compete for limited funds.
Use Predictable Savings Routines
Adopt small, automated routines that funnel money into the designated education buckets on a schedule that matches household cash flow.
Automation reduces the need for manual transfers and ensures progress toward goals, while modest recurring contributions compound into meaningful funding over time.
Review, Reallocate, and Keep Decisions Visible
Schedule a quarterly or annual review to compare actual spending to your policies and reallocate funds when priorities change.
Make decisions transparent to all household members affected by education funding so trade-offs are understood and agreed upon before commitments are made.
Conclusion
Clear rules, tiered funding, and routine savings create predictable education spending. Regular reviews and visible decisions keep the plan realistic and flexible. Applied consistently, this framework lowers stress and preserves overall household stability.