Allocating household funds for learning milestones helps families make intentional choices about what to fund and when. Begin by mapping key learning events, estimating costs, and matching them to realistic cash flow windows. This process reduces last-minute decisions and creates clarity about trade-offs among competing priorities. A clear, repeatable approach also makes it easier to adjust when circumstances change.
Define Milestones and Timeline
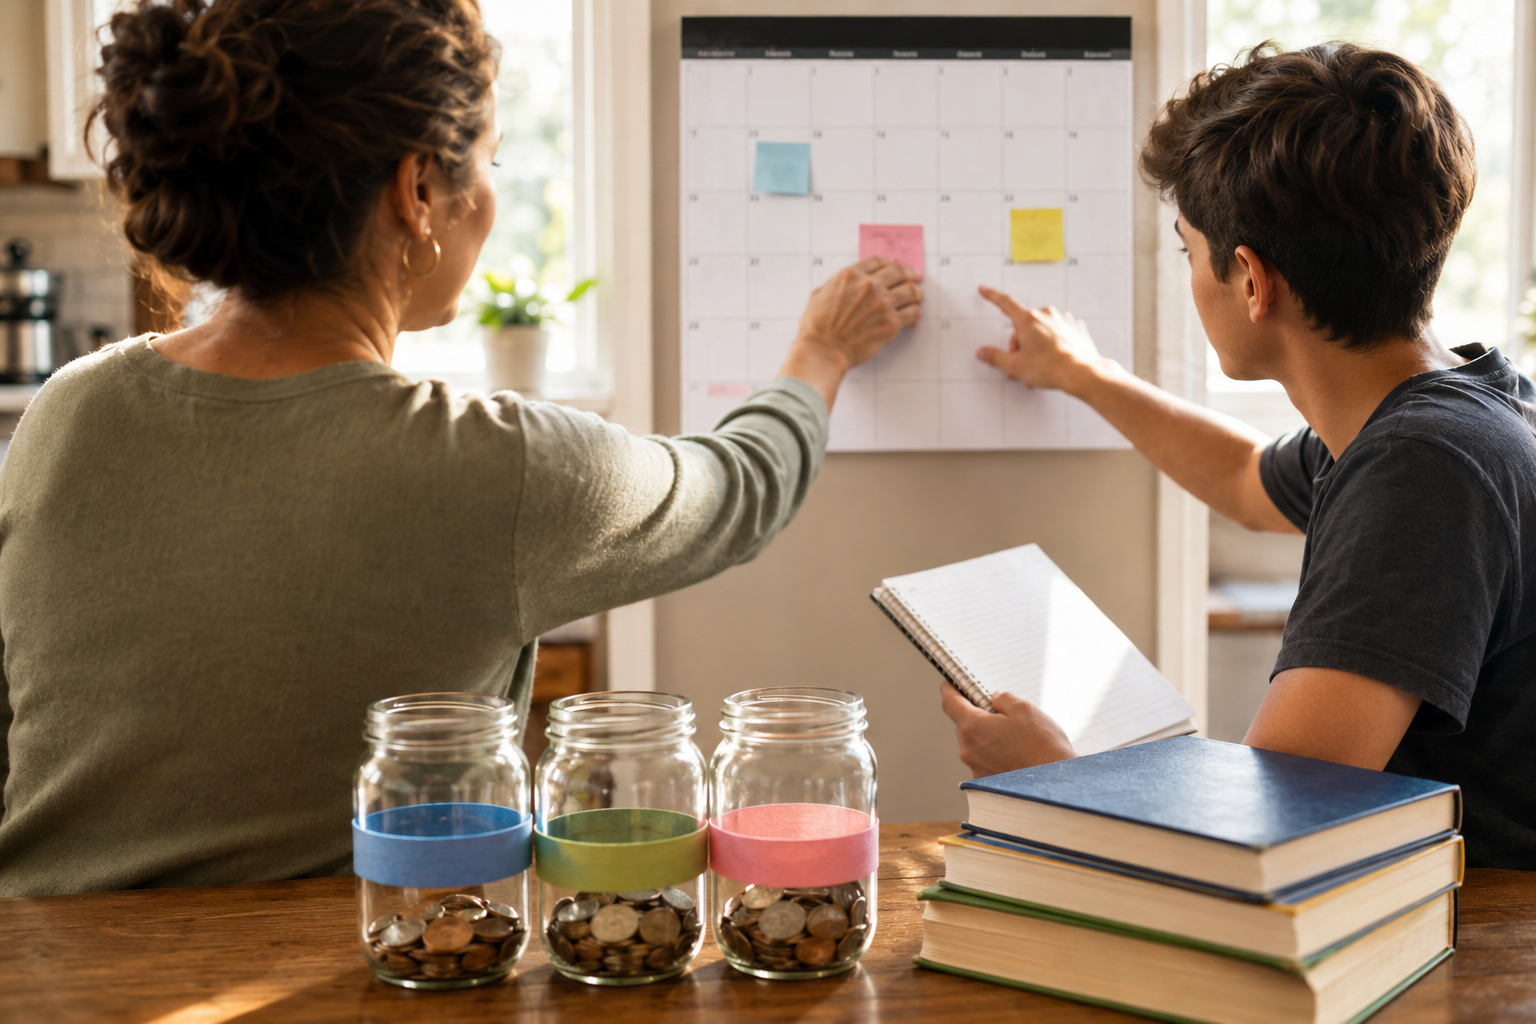
Start by listing specific learning milestones you expect to support, such as early enrichment, vocational training, or certification courses. For each item note an estimated cost, ideal timing, and any prerequisites that could shift the schedule. Group similar events by short-, medium-, and long-term timing to see how they compete for resources. This step turns vague intentions into a visible roadmap.
When you know the timing and magnitude of each milestone, prioritizing becomes a disciplined exercise rather than an emotional one. You can then allocate funds more confidently against a planned schedule.
Create Tiered Funding Buckets
Design funding buckets that reflect priority and urgency: essentials, development, and aspirational learning. Allocate predictable monthly or quarterly contributions to each bucket so the funding accumulates ahead of need. Keep the buckets in accessible accounts with clear rules about when money moves from bucket to purpose. This structure prevents one unexpected cost from derailing other planned learning investments.
- Essentials: recurring fees, required materials.
- Development: planned courses or workshops.
- Aspirational: higher-cost degrees or specialized programs.
By separating funds, you maintain flexibility while preserving intent, making it easier to reassign lower-priority money if needed.
Set Decision Rules and Triggers
Establish simple rules that guide whether to proceed, pause, or seek alternatives when a learning opportunity arises. Common triggers include available bucket balance, expected return (skills or income), and alignment with household goals. Define thresholds—for example, require at least 60% of the estimated cost in the bucket before committing. These rules reduce friction and help families make consistent choices under pressure.
Decision rules also create a shared language for household conversations about trade-offs. That clarity lowers conflict and speeds decisions.
Monitor, Review, and Adjust
Schedule quarterly reviews to compare actual spending to your roadmap and adjust estimates or timelines as needed. Track outcomes as well as costs: note skills gained, credentials earned, and how each investment affected household goals. Small course corrections prevent minor mismatches from becoming systemic problems. Keeping records makes future planning faster and more accurate.
Regular reviews allow you to reallocate resources responsibly and to capture lessons for future cycles. This iterative approach keeps your funding aligned with changing needs.
Conclusion
Turn vague intentions into an actionable plan by defining milestones, creating tiers, and setting clear decision rules. Regular monitoring and simple reallocation rules keep plans resilient and aligned with household priorities. With this structure, funding learning becomes a manageable, predictable part of family finances.