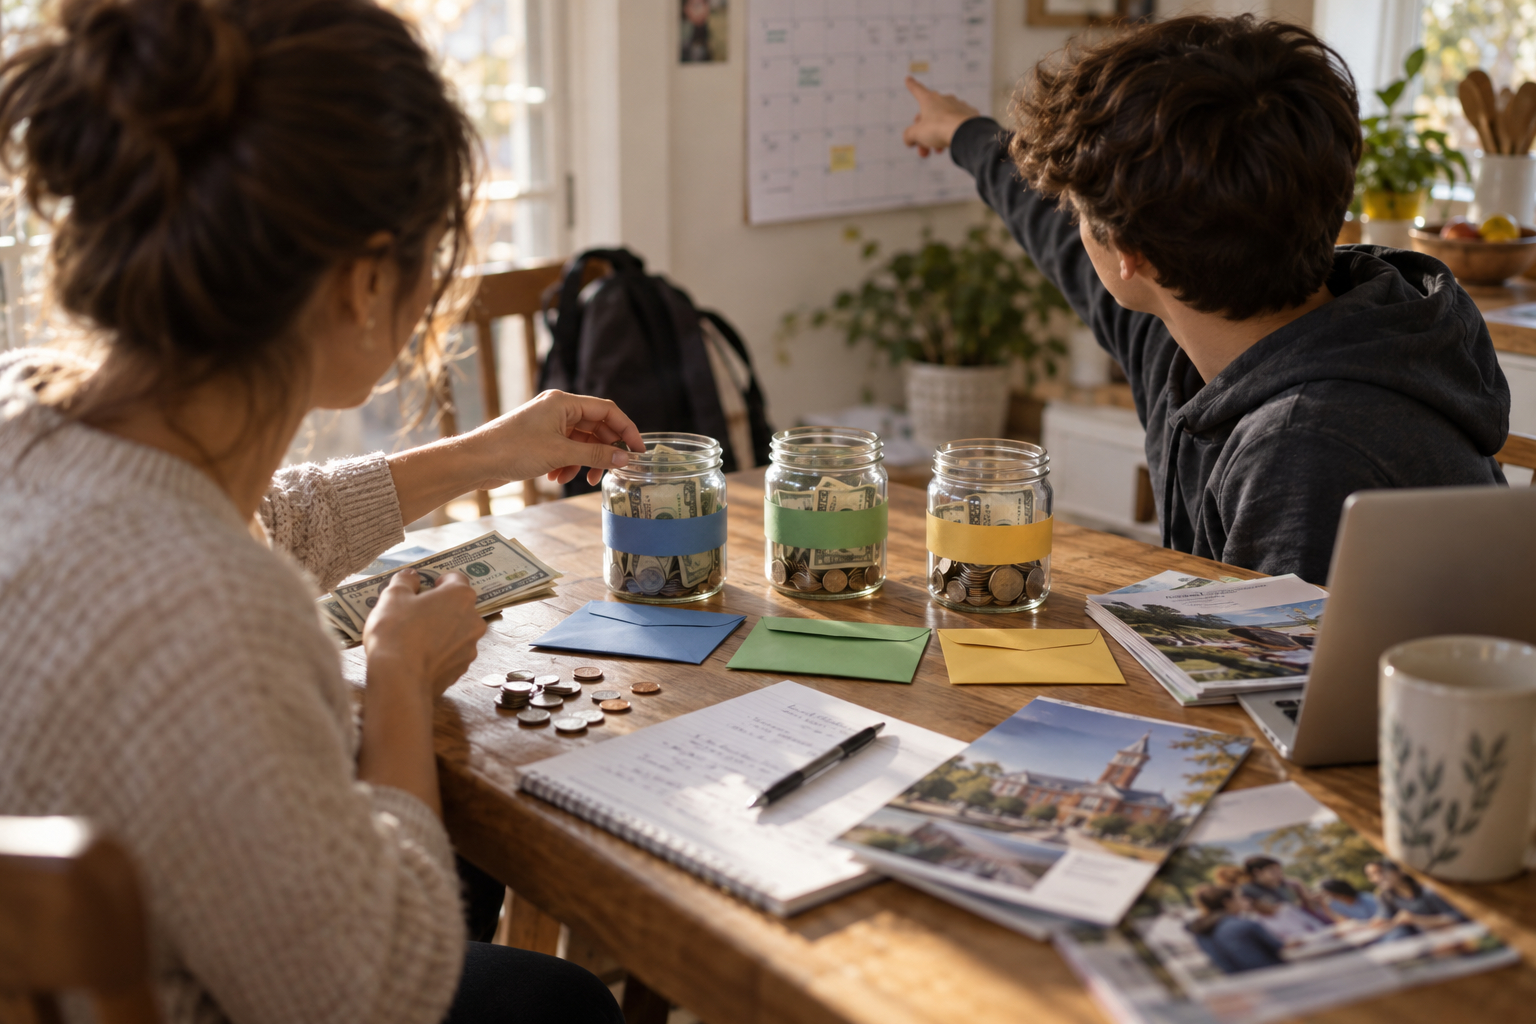
Managing household education expenses requires a clear, repeatable approach that balances timing, priorities, and cash flow. A modular funding strategy divides costs into purpose-built buckets — immediate, near-term, and long-term — so decisions align with affordability and goals. This approach reduces the need for last-minute tradeoffs and makes it easier to accept pauses or lower-cost alternatives when priorities shift. It also helps households capture opportunities like employer support, scholarships, or seasonal discounts without disrupting core finances. The rest of this article lays out practical steps to assess needs, create funding modules, and set operational rules for ongoing management.
Assessing Needs and Timing
Start by mapping education commitments across a realistic timeline. Include recurring costs like subscriptions and training, one-off courses, and major milestones such as certification programs. Assign approximate costs and preferred timing to each commitment, and note which items are flexible versus essential. This inventory creates the clarity needed to size each funding module appropriately.
With a clear map, you avoid overfunding low-priority items and under-reserving for critical ones. That discipline keeps household finances aligned with real learning goals.
Building Modular Funding Buckets
Create three modular buckets: immediate (current term), near-term (next 6–18 months), and long-term (beyond 18 months). Fund the immediate bucket from regular cash flow so ongoing courses are uninterrupted, while the near-term bucket can use a rolling savings plan sized by upcoming commitments. The long-term bucket focuses on larger investments and can be a mix of earmarked savings and investments calibrated to the time horizon. Each module has a clear funding target, acceptable funding sources, and a trigger to use the funds.
Treat each bucket as a purpose-driven account rather than loose savings. That makes it easier to prioritize when multiple needs compete.
Operational Rules and Regular Review
Operational rules turn plans into habits: set a contribution schedule, define pause criteria, and identify contingency options such as credit, employer assistance, or scholarship searches. Automate transfers where possible and schedule biannual reviews to compare projections with actual spending. Use simple rules to reallocate surplus or shortfalls—examples include moving a percentage of any windfall to the near-term bucket. Clear rules reduce decision fatigue and keep the strategy resilient.
Consistency beats perfection; small, steady contributions build capacity over time. Regular reviews ensure the system adapts to changes in income and priorities.
Conclusion
Adopting a modular funding strategy creates predictability and flexibility for household education expenses. It encourages deliberate choices and preserves cash flow for essentials. Implement the steps gradually and refine the rules each cycle.
Related Articles
Recent Posts

Calibrating Household Budgets for Education Cost Fluctuations
Designing Milestones for Household Education Funding Stability
Building Student Routines That Support Steady Learning Gains
Crafting Daily Mini-Routines to Boost Learner Independence
Empowering Learners Through Compact Personalized Study Plans


