Education costs are a major concern for learners and families planning for the future. Understanding where expenses arise and how to prepare can reduce stress and improve outcomes. Early planning and disciplined habits turn uncertain costs into manageable investments. This article outlines practical steps to assess, save, and manage education-related spending.
Assessing Education Costs
Begin by breaking down all potential costs into clear categories such as tuition, materials, living expenses, and incidental fees. Research realistic price ranges for each category at different institutions and programs to avoid surprises. Include nonobvious items like transportation, technology upgrades, and exam or certification fees in your estimates. A comprehensive assessment reveals where cuts or extra savings will have the biggest impact.
Once you have a complete list, prioritize expenses by necessity and potential return on investment. This helps guide decisions about program selection, part-time work, or alternate learning formats.
Effective Saving Strategies
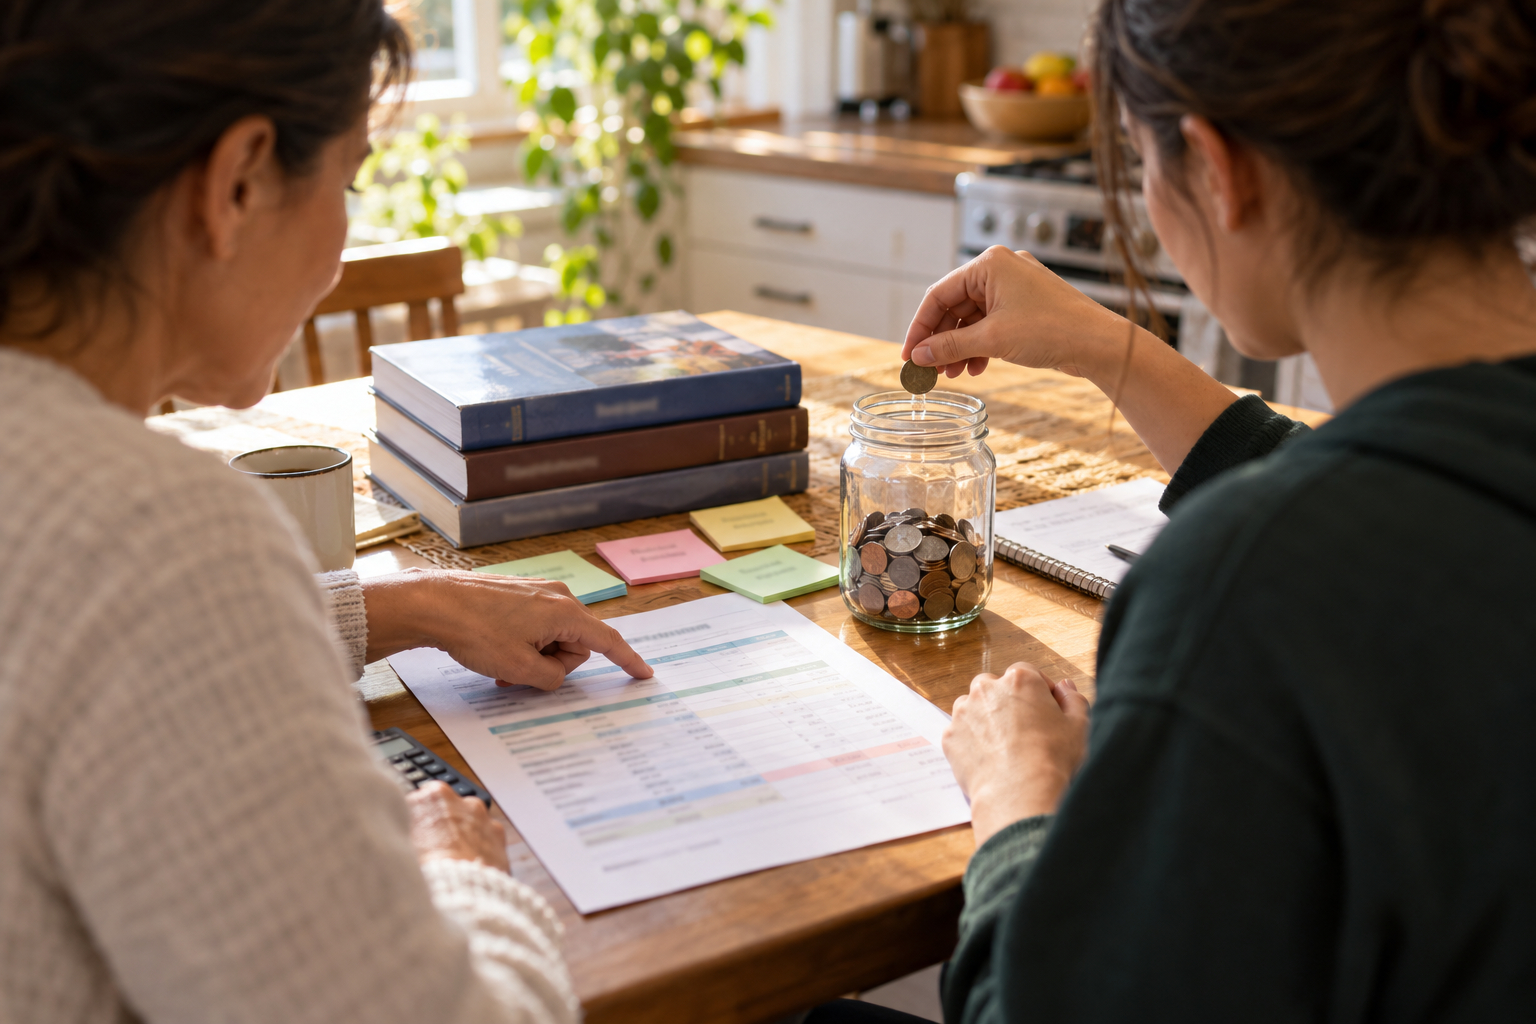
Consistent saving habits are the backbone of a solid education funding plan. Set a specific savings goal and automate contributions to a dedicated account to build momentum and avoid temptation. Consider tax-advantaged accounts if available and compare short-term savings tools for flexibility and growth potential. Small, regular contributions compounded over time can significantly reduce future borrowing needs.
- Create a monthly savings plan tied to income and essential expenses.
- Look for institutional scholarships and community grants early.
- Use comparison shopping for books and supplies to minimize costs.
Combining automated savings with active cost-cutting measures preserves both financial flexibility and academic focus.
Managing Loans and Financial Aid
When loans are necessary, understand the terms, interest rates, and repayment options before borrowing. Prioritize grants and scholarships that do not require repayment and explore work-study or part-time opportunities that align with career goals. If multiple loan options exist, choose those with favorable interest rates and protections, and consider starting interest payments while still studying if feasible. Regularly review your aid package and reapply for assistance as circumstances change.
Develop a repayment plan that balances debt reduction with ongoing savings, and seek professional counseling for complex situations.
Conclusion
Managing education expenses requires clear assessment, consistent saving, and informed borrowing decisions. Small planning steps taken early can prevent large financial burdens later. By prioritizing necessities, seeking aid, and maintaining disciplined habits, education becomes an achievable investment rather than an overwhelming cost.