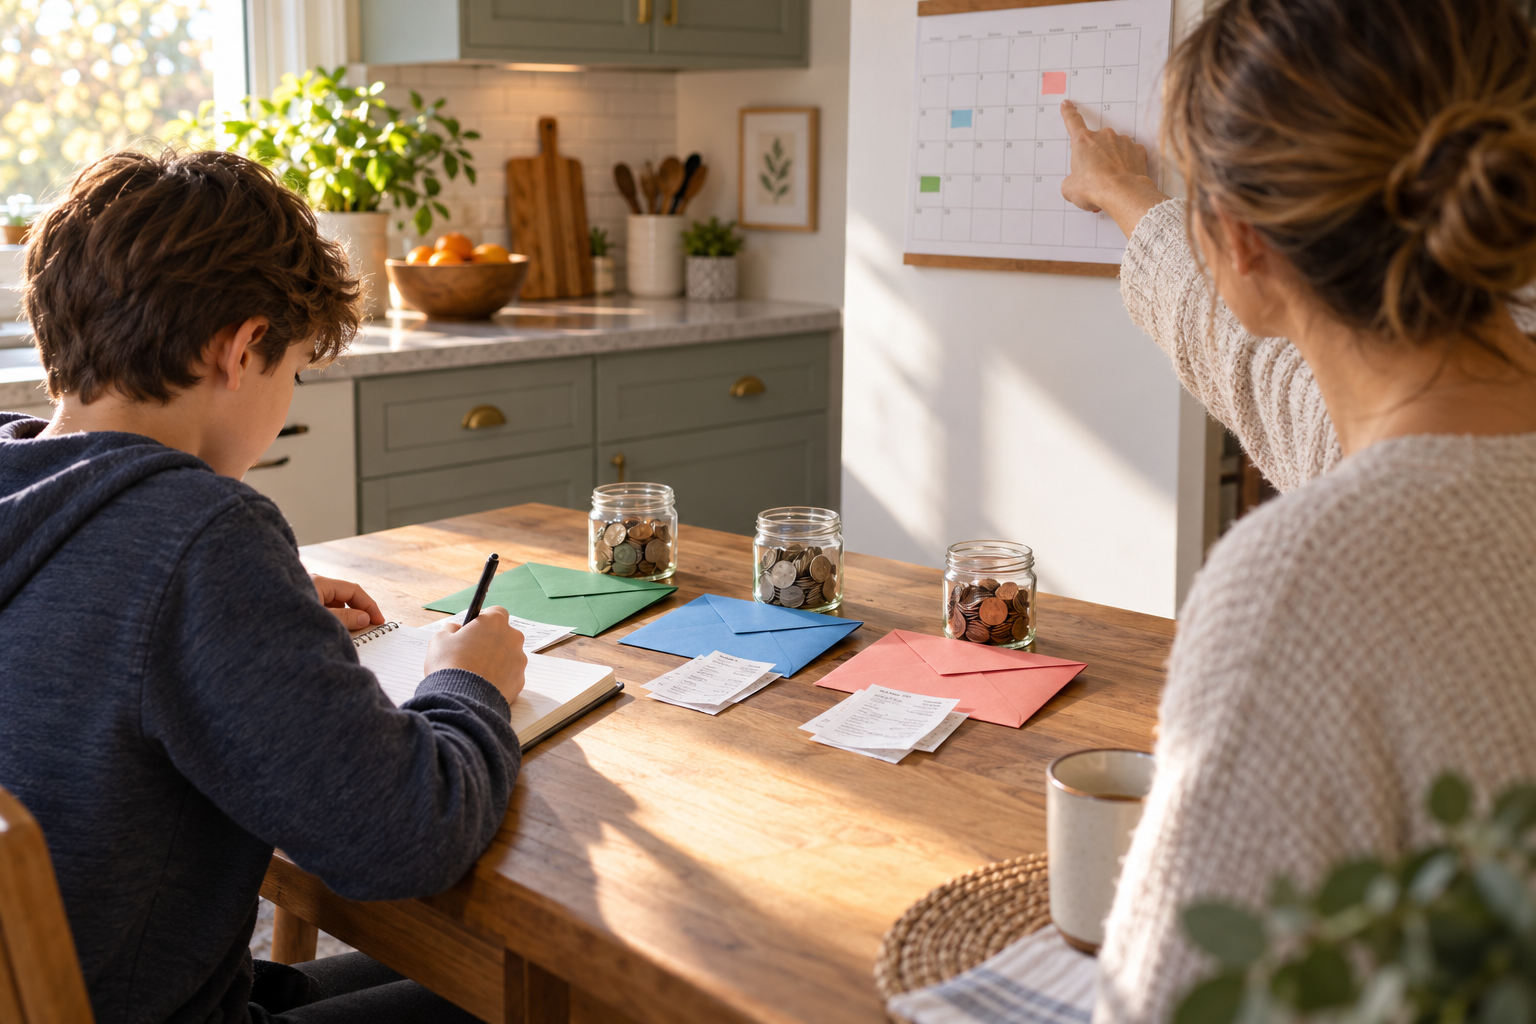
Education costs in households can be irregular and quickly strain monthly budgets. Building a practical roadmap helps turn one-off requests into predictable, documented choices. This article outlines steps to assess needs, create funding buckets, align timing, and keep decisions under review. The goal is a repeatable system that reduces stress and supports learning priorities.
Assess and Prioritize Education Needs
Start by taking a clear inventory of current and anticipated education expenses. Include recurring fees, supplies, course fees, exam costs, and informal learning opportunities that tend to be overlooked. Assign a priority to each item based on timing, importance, and who benefits most. This assessment creates evidence to guide funding decisions rather than reacting to requests.
- List recurring and one-time costs with expected dates.
- Note who benefits and whether alternatives exist.
- Estimate amounts conservatively to avoid surprises.
Use simple spreadsheets or a budgeting app to track this inventory regularly. Updating priorities every quarter keeps the list aligned with real household needs.
Design Tiered Funding Buckets
Create tiered funding buckets that separate essential commitments from aspirational learning. Essentials cover required tuition and certificates, developmental funds support ongoing skills, and opportunistic money captures one-off workshops or scholarships. Size each bucket relative to priority and available cash flow, and set simple rules for transfers and approvals. Clear labels and rules reduce debate and speed decisions.
- Essentials: required payments and mandatory exams.
- Developmental: ongoing training and subscription learning.
- Opportunistic: short courses, conferences, or trial classes.
Consider separate savings accounts or virtual envelopes to make progress visible. Avoid mixing funds so that urgent commitments are not eaten by optional activities.
Align Cash Flow, Timing, and Contingencies
Match funding timing to when costs occur by using a calendar-first approach. Plan transfers a month ahead of major bills and build a modest contingency buffer for unexpected fees. Automate transfers where possible and keep one reserve for emergencies that prevents pulling from developmental or opportunistic buckets. This alignment keeps cash flow stable while honoring learning commitments.
- Automate monthly transfers to each bucket.
- Set a calendar reminder for large annual or semester bills.
Revisit buffer levels annually and after any major lifecycle change. Small, predictable habits prevent last-minute borrowing and stress.
Review, Adjust, and Record Decisions
Set a regular review—quarterly or semiannual—to evaluate outcomes against priorities and expenses. Record decisions about funding so that future members of the household understand the rules and rationale. Use these reviews to reallocate funds, pause nonessential subscriptions, or accelerate savings for an upcoming milestone. Keeping records also reveals patterns that can reduce recurring overspend and highlight savings opportunities.
Share results in a short household meeting to maintain alignment. Iteration is the expected path, not perfection.
Conclusion
A practical roadmap turns education expenses into manageable decisions. By assessing needs, creating buckets, aligning timing, and reviewing choices, households can support learning without financial stress. Regular, simple habits sustain this system over time.
Related Articles
Recent Posts

Synchronizing Education Funds with Monthly Income Cycles
Everyday Budget Habits That Ease Education Cost Surprises
Designing Compact Choice Menus to Foster Student Decision-Making
Teaching Students to Sequence Tasks for Deeper Engagement
Practical Classroom Methods for Teaching Strategic Study Prioritization


