Managing education expenses requires a practical system that matches timing, priorities, and household cash flow. Rather than guessing, a clear approach helps reduce surprises and keeps learning goals on track. This article outlines repeatable steps to assess needs, create intentional savings buckets, and adjust funding as circumstances change. The aim is to give actionable guidance that works for different stages and resource levels.
Assessing Needs and Timing
Begin by mapping upcoming education costs against realistic timelines. Identify short-term workshops, annual fees, and longer commitments such as multi-year programs and certifications. Attach estimated amounts and dates to each item so you can prioritize which need immediate saving. This inventory becomes the foundation for any funding strategy.
Use the map to set priorities based on urgency, impact, and affordability. Regularly revisit estimates to account for changes in scope or price.
Creating Purposeful Savings Buckets
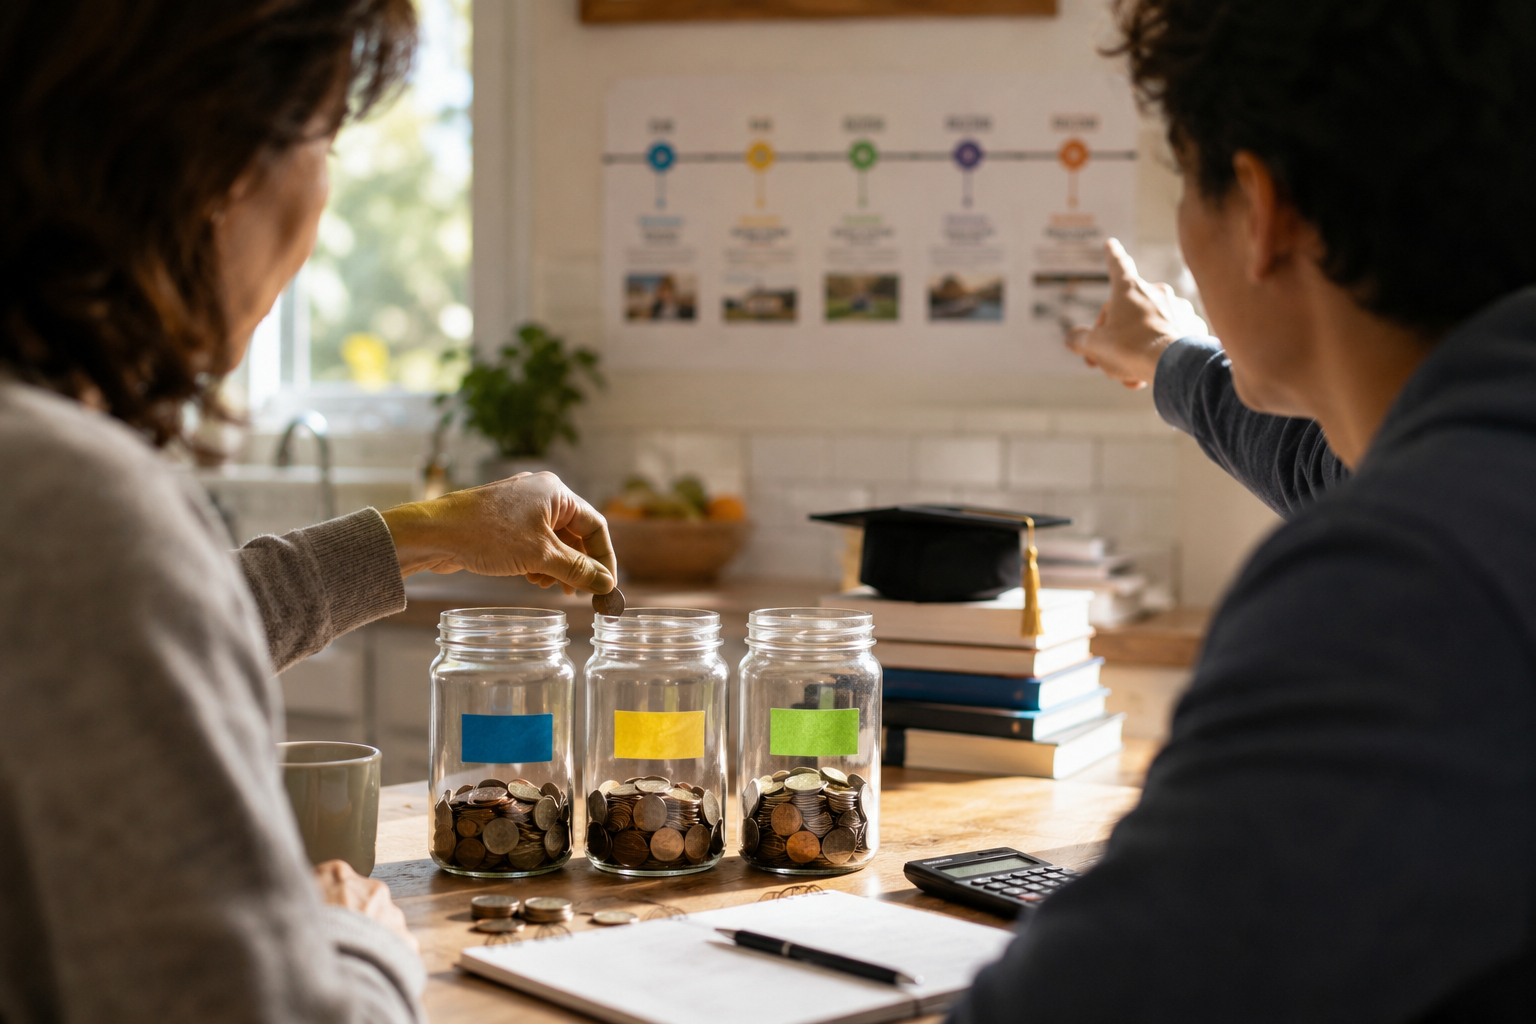
Create distinct buckets that reflect purpose rather than arbitrary categories. For example, one bucket for required tuition, another for optional enrichment, and a third for emergency learning opportunities. Label each account or spreadsheet entry with a clear goal and target date so contributions remain focused. Small, consistent transfers into these buckets compound into reliable funds over time.
- Essential tuition: predictable, planned payments.
- Enrichment: workshops, books, and short courses.
- Opportunity fund: ad hoc chances to pursue high-value learning.
Automate contributions where possible and set minimum balances to signal readiness. Treat reallocation as a deliberate choice, not an ad hoc reaction.
Managing Cash Flow and Adjustments
Match contribution size and frequency to your cash flow using simple rules, such as percentage-of-income or flat monthly amounts. During tight months, prioritize essential buckets and pause discretionary contributions temporarily. Use small windfalls — tax refunds, bonuses, or gifts — to catch up or seed a new goal. Track progress monthly to avoid last-minute scrambles and to celebrate steady wins.
Adjust targets annually and after major life events to keep the plan realistic. A flexible, monitored approach prevents education spending from becoming a financial shock.
Leveraging Community and Alternative Funding
Investigate scholarships, employer tuition assistance, and community partnerships as part of routine planning. These sources can substantially reduce out-of-pocket needs and often align with specific skill gaps employers value. Peer learning groups and shared resources also lower costs through pooled materials or reciprocal teaching. Including these options in your inventory lets you compare true net costs across different pathways.
Make applying for external funds a standard task when setting goals, not an afterthought. Regular outreach to networks can open unanticipated opportunities that fit existing timelines and budgets.
Conclusion
Building structured, purpose-driven funds for education makes learning aims achievable. Focus on timelines, buckets, and simple rules that fit your cash flow. Over time, small disciplined steps translate into steady readiness for education expenses.