Managing education expenses requires a practical, repeatable approach that fits household cash flow and priorities. Small structural choices—how you group costs, schedule payments, and set rules—reduce uncertainty and friction. This article outlines steps to create funding buckets, align expenses with income cycles, and monitor outcomes. The goal is a sustainable system that minimizes surprises while keeping learning priorities intact.
Assess Costs and Timing
Begin by cataloguing expected education costs over the next 12–24 months and noting when payments are due. Distinguish recurring fees, infrequent large expenses, and optional learning investments to clarify priorities. Include realistic estimates for materials, transportation, and incidental costs so you avoid underfunding. This assessment gives a clear map of obligations and flexible opportunities.
Use the results to set funding targets. Revisiting the list quarterly keeps it current.
Create Tiered Funding Buckets
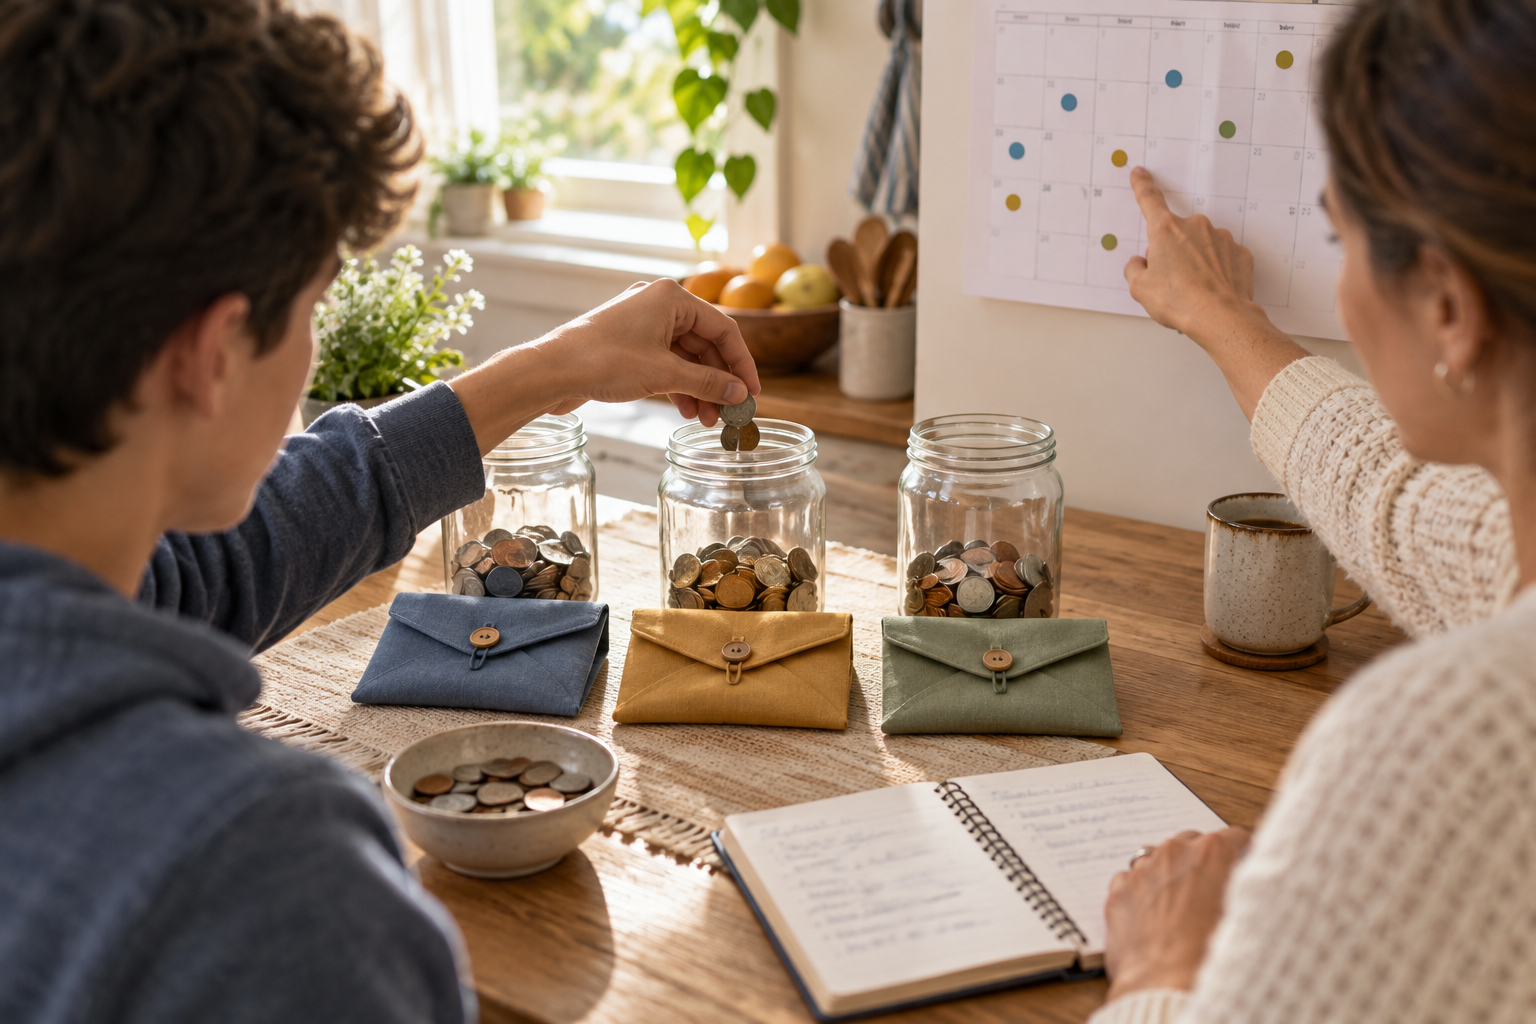
Separate funds into simple tiers: essential recurring costs, planned lump-sum expenses, and discretionary learning. Assign target balances and funding rules for each tier so decisions become mechanical rather than emotional. Automate transfers where possible to build buffers slowly without active effort. A modest emergency buffer for unexpected education costs prevents derailing other budgets.
Label accounts clearly and track balances monthly. This clarity speeds decisions when opportunities or conflicts arise.
Align Payments with Cash Flow
Match payment schedules to your income rhythm to avoid shortfalls. When possible, ask providers about alternative billing dates, instalments, or early payment discounts that better fit monthly cycles. If income is irregular, prioritize building a small float equal to one month of typical education outflows. Strategic timing reduces the need for last-minute borrowing or cutting other essential spending.
Plan transfers to occur shortly after your main income arrives. This creates a simple cadence you can maintain.
Practical Funding Rules
Establish a few simple rules everyone follows to keep the system manageable. Examples: fund essentials first, cap discretionary spends at a percentage, and require consensus for big new courses. Keep rules written and visible so decisions are quick and consistent. These constraints make it easier to evaluate tradeoffs when offers or new needs arise.
Review these rules annually and tweak them as income or priorities shift. Simple rules make execution straightforward.
Monitor, Adjust, and Communicate
Regularly review spending against targets and adjust funding rules as needs change. Keep a short record of decisions—what was postponed, what was accelerated, and why—so you can refine priorities over time. Communicate rules and trade-offs with household members to ensure alignment and avoid surprises. Transparency makes it easier to pause discretionary spending when constraints appear.
Set a quarterly check-in and a simple dashboard of balances and upcoming payments. Small, regular adjustments keep the system resilient.
Conclusion
Stabilizing education spending is about structure, timing, and simple rules. Implement tiered buckets, align payments with income, and review regularly to keep plans realistic. Over time the system reduces stress and preserves learning priorities.