Managing ongoing learning costs requires a straightforward, repeatable approach that matches timing, priority and household cash flow. This article outlines a compact framework that helps households forecast expenses, allocate funds, and adjust without constant stress. The goal is to turn irregular education bills into predictable, manageable commitments. Readers will find practical steps to set priorities and create funding buffers that fit real life.
Define priorities and schedule expenses
Start by listing planned learning activities and their approximate dates and costs, from short courses to certification renewals. Assign each item a priority level based on impact, urgency and available alternatives, so discretionary choices become easier during tight months. Estimating timing is critical: group expenses by when they are due rather than by how appealing they are. This reduces last-minute scrambling and helps align savings with actual cash flow.
Once priorities and timing are clear, you can target savings and identify which items might be postponed or funded through alternative sources. Clear priorities make trade-offs transparent and simpler to communicate within a household.
Build modular savings buckets tied to timing
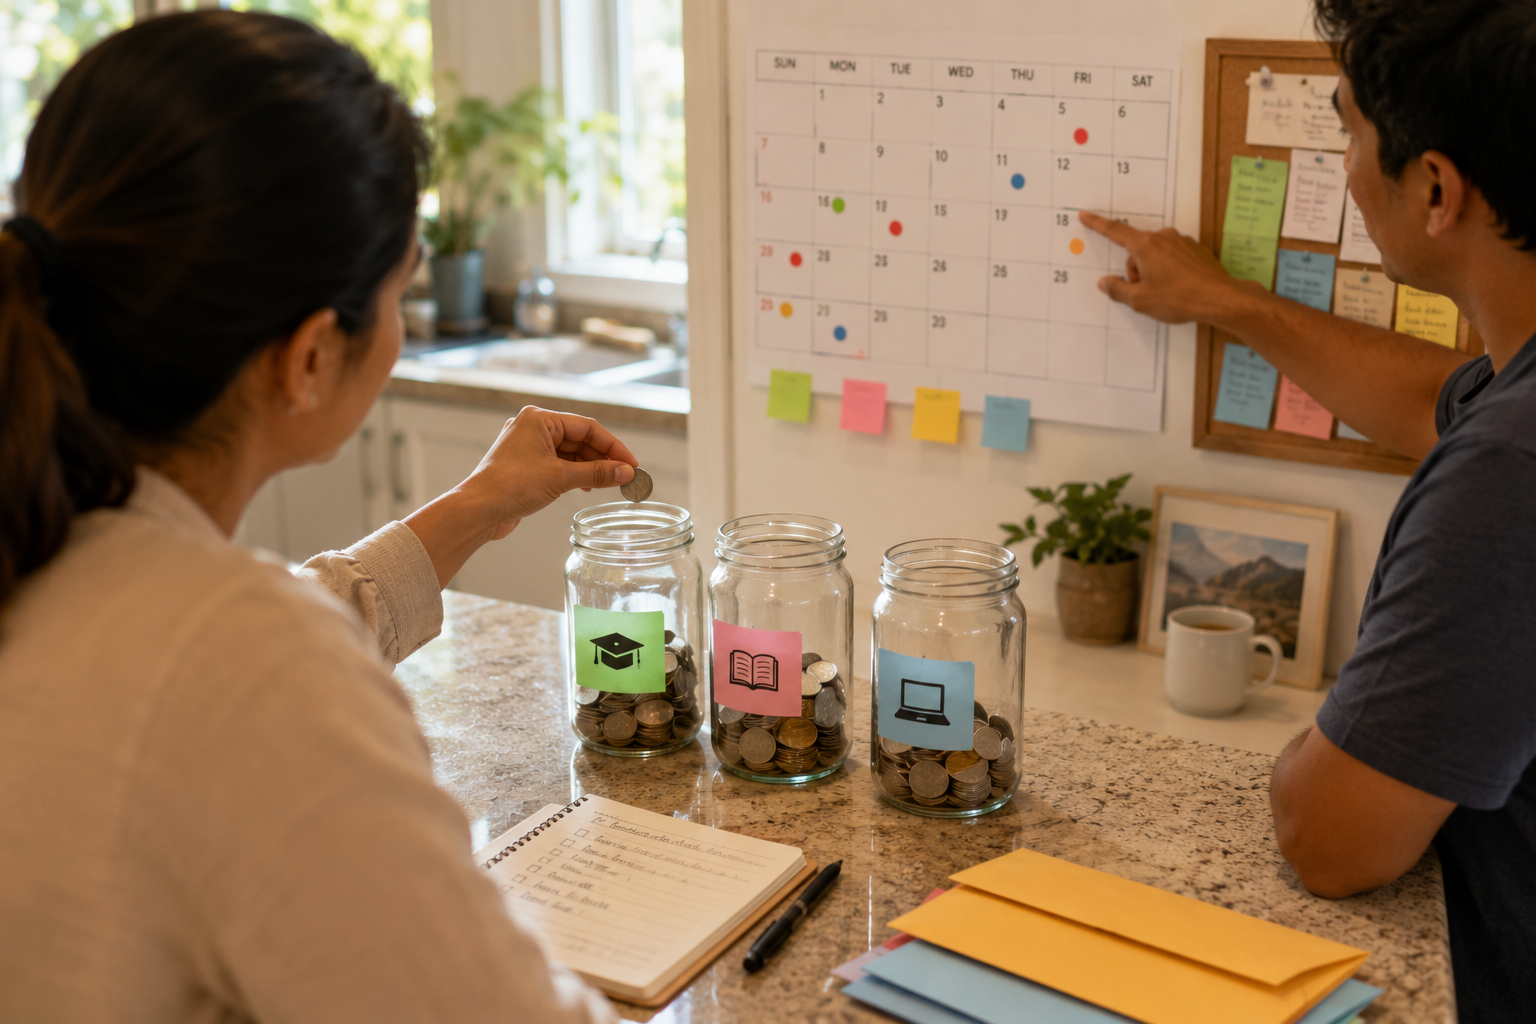
Create separate, named buckets for short-term and medium-term learning goals so money is easy to track and reassign. Keep a rolling bucket for predictable annual costs, a short-term bucket for courses within six months, and a contingency buffer for unexpected opportunities or price increases. Small, automatic transfers timed to pay periods make contributions consistent and reduce decision fatigue. Treat each bucket as a mini-account with a clear funding target and a deadline to keep momentum.
- Annual renewals: a fixed monthly transfer that totals the yearly cost.
- Upcoming courses: monthly contributions sized to meet the registration date.
- Opportunity fund: a modest cushion for one-off chances or emergencies.
These buckets let you see progress and reallocate funds without disrupting other household goals. Over time, they also smooth spikes in spending.
Create simple cash-flow rules and review cadence
Adopt rules that guide decisions, for example prioritizing mandatory certifications over elective workshops when funds are limited. Limit ad-hoc spending by requiring a short decision pause or a simple checklist to confirm alignment with priorities. Schedule a lightweight quarterly review to move funds, adjust targets, and record lessons learned. Regular reviews keep the system responsive without becoming a burden.
Clear rules combined with a steady review rhythm keep learning on track and prevent surprise expenses from derailing plans. Small adjustments during reviews compound into reliable funding over time.
Conclusion
Use timing, prioritized buckets and simple rules to make learning expenses predictable and manageable. Automate contributions and review targets quarterly to maintain flexibility while protecting household cash flow. With this framework you can fund ongoing education without constant stress or paperwork.