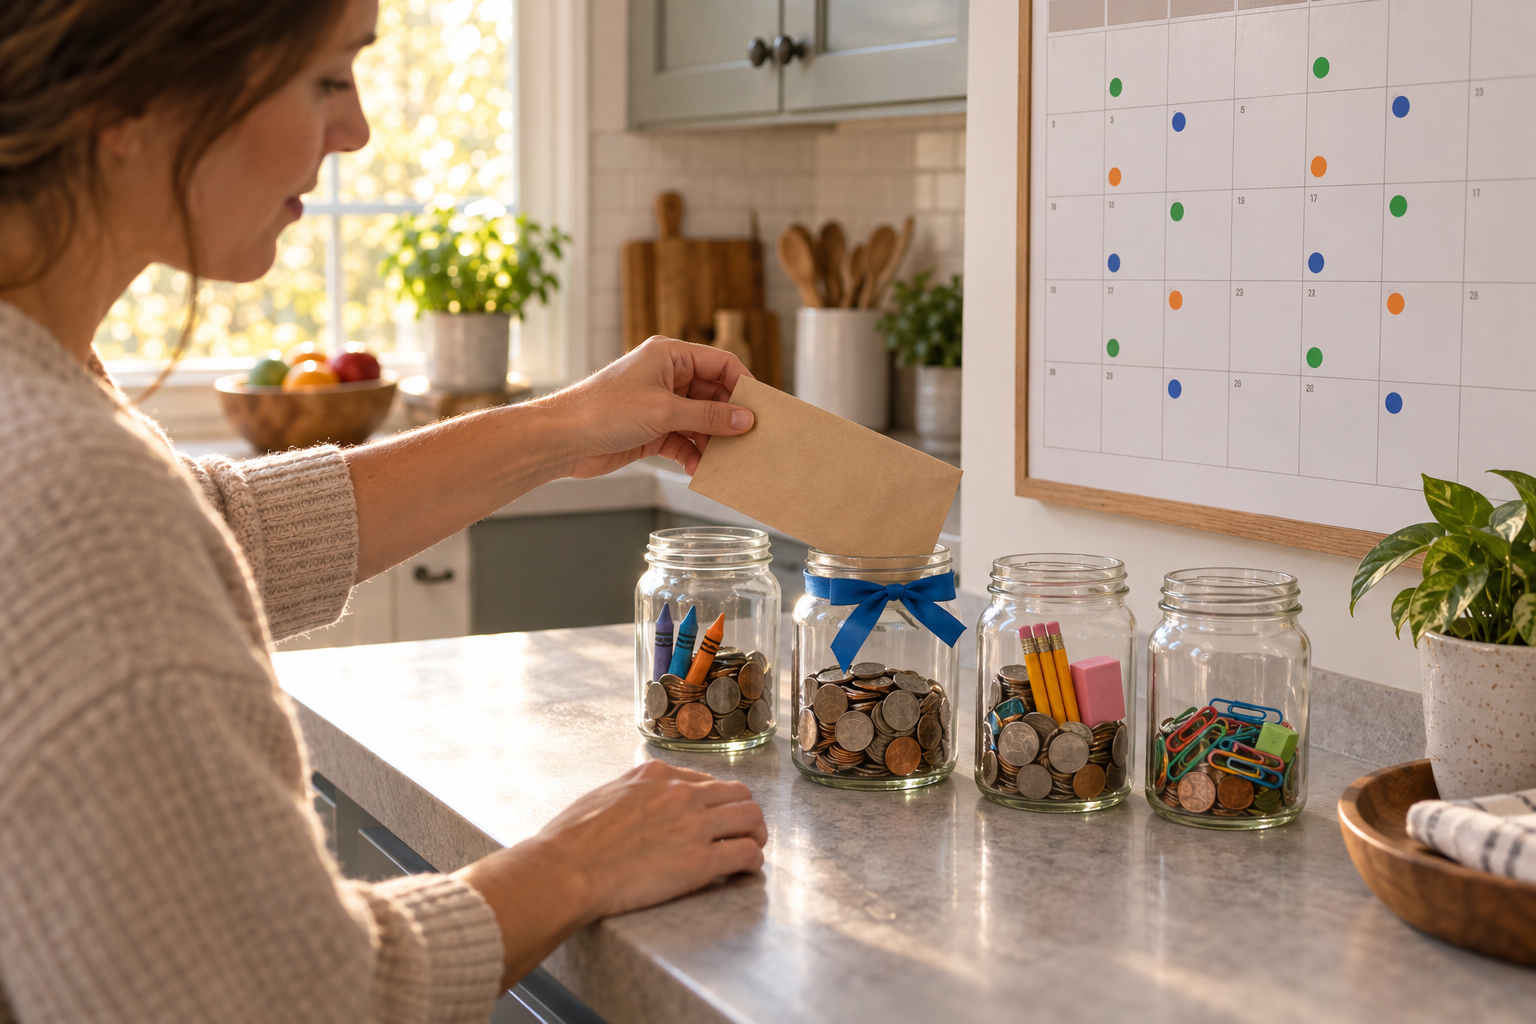
Planning education spending around income cycles reduces surprises and helps maintain long-term learning goals. By mapping due dates and program timing to paydays you can smooth cash flow and avoid last-minute borrowing. This approach prioritizes timing, small buffers, and repeatable rules rather than complex forecasts. The result is a manageable, resilient plan that fits everyday household routines.
Assess Timing and Priorities
Start by listing upcoming education expenses and when they fall in the year. Include tuition installments, course fees, materials, testing costs, and any recurring subscriptions. Note which items are flexible and which have fixed deadlines so you can sequence payments with income arrivals. This inventory reveals pockets of pressure and opportunities to shift timing.
Use that schedule to decide what must be pre-funded and what can be paid as you go. Clear visibility reduces the temptation to cut essential items when cash is tight.
Create a Rolling Monthly Education Budget
Set up a rolling monthly education budget tied to your pay cycle instead of an annual lump-sum target. Allocate a fixed percentage or amount from each paycheck to designated education funds so contributions are automatic and predictable. Keep one short-term buffer for the next three months of obligations and a longer-term account for planned milestones. Automating transfers reduces decision fatigue and keeps funds available when bills arrive.
Adjust the contribution amount after major life changes or at least once a year. Small, consistent amounts compound into reliable coverage without derailing other goals.
Use Simple Rules to Stay Flexible
Adopt simple rules to handle changes: prioritize mandatory fees, pause discretionary courses when needed, and reallocate funds before borrowing. These rules make trade-offs explicit and fast, reducing stress. Maintain a modest contingency so unexpected registration windows or course materials don’t force high-cost borrowing. Periodic reviews keep the plan aligned with shifting household priorities.
- Priority rule: always fund mandatory tuition first.
- Buffer rule: maintain one pay period’s worth of education spending.
Documenting the rules in writing makes them easy to follow during busy months. Share them with household members so everyone understands how decisions are made.
Monitoring and Adjusting
Track actual spending against the planned calendar each month to spot variances early. Use simple metrics: percent of planned funds used, number of deferred items, and buffer remaining. When patterns show recurring shortfalls, revisit priorities and contribution rates rather than one-off cuts. Small adjustments keep the system sustainable and prevent late fees or rushed choices.
Set a quarterly reminder to review and update the schedule. Over time the process becomes routine and less demanding.
Conclusion
Synchronizing funds to income cycles simplifies decision-making and reduces surprises. Automatic contributions and simple rules keep education spending sustainable. Regular reviews ensure the system adapts as needs change.
Related Articles
Recent Posts

Practical Roadmap for Household Education Expense Management
Everyday Budget Habits That Ease Education Cost Surprises
Designing Compact Choice Menus to Foster Student Decision-Making
Teaching Students to Sequence Tasks for Deeper Engagement
Practical Classroom Methods for Teaching Strategic Study Prioritization


