Many individuals and households face the challenge of funding training, courses, and certifications when income is uneven month to month. Variable pay can make education spending feel risky and easy to postpone, which undermines long-term goals. Turning irregular income into reliable funding starts with a clear cash-flow plan and simple rules that scale with seasonal changes. This piece outlines a step-by-step approach to assess rhythms, set up tiers of funds, and adopt habits that keep learning on track.
Assess Your Income Rhythm
Begin by mapping income across a representative period, such as six to twelve months, to reveal patterns and outliers. Calculate an average monthly amount as a baseline, then flag months that consistently produce surpluses or deficits. Understanding which months reliably deliver extra cash lets you schedule larger learning expenses when capacity is highest. This assessment is the foundation for predictable funding decisions that respect real cash flow.
Once you have the rhythm identified, convert those insights into concrete rules. For example, reserve a percentage of every surplus month for educational use and avoid tapping that reserve in lean months.
Create Tiered Funds
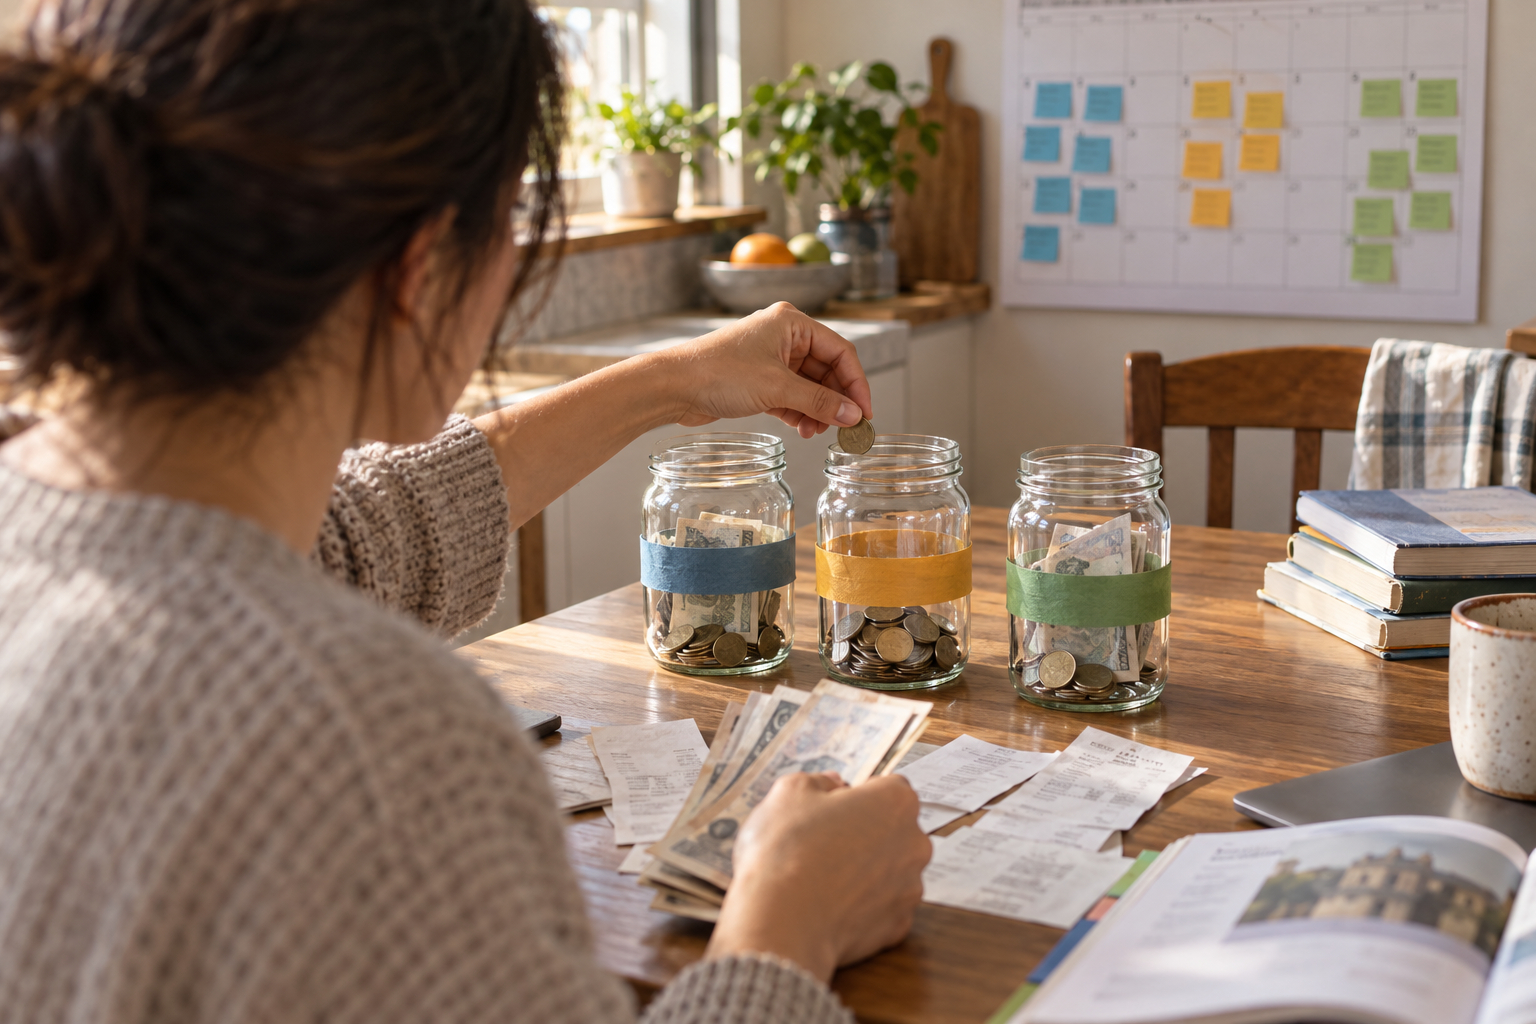
Design three practical tiers: a small immediate buffer for upcoming bills, a planned bucket for scheduled courses, and an opportunity fund for unexpected chances. The immediate buffer covers short-term timing mismatches so you do not cancel an important class due to a cash gap. The planned bucket aligns with registered courses and certification timelines, funded steadily from average monthly allocations. The opportunity fund grows slowly and is used for high-value chances that align with your priorities.
- Immediate buffer: one to two months of typical education spending.
- Planned bucket: allocate a fixed monthly amount toward scheduled expenses.
- Opportunity fund: save a modest portion of surplus months for special chances.
Label and track each tier so transfers and withdrawals are habitual, not ad hoc. Clear labels reduce decision friction and keep funds available when needed.
Implement Low-Lift Habits
Simplify the mechanics with automation and small routines: set automatic transfers when pay arrives, round up to the nearest saving increment, or sweep a portion of freelance payments into the appropriate tier. Revisit allocations quarterly to adjust percentages as income and priorities shift, and communicate rules with household members or partners to avoid ad hoc spending. Small, repeatable actions outperform occasional big efforts because they adapt to fluctuating cash flow. Over time these habits build a reliable runway for continuous learning.
Keep the system lean and review only the numbers that matter to avoid decision fatigue. Regular but light maintenance preserves both flexibility and discipline.
Conclusion
Irregular income does not have to block education goals when you adopt a rhythm-based funding approach. By assessing income patterns, creating tiered funds, and applying low-lift habits, you convert variability into predictable support for learning. Start small, automate where possible, and adjust as you learn to keep progress steady.